Powered Shell vs. Turnkey vs. Colocation: What Each Delivers and What It Costs
A powered shell data center is a building delivered with structure, utility power and fiber entries but without the UPS, generators or cooling plant; the tenant installs and owns those. Turnkey, also called build-to-suit, delivers the finished and commissioned facility, and the landlord keeps the plant. Colocation sells slices of a turnkey building by the kilowatt. In 2026 the cost ladder runs from about $584,000 per MW for powered land to $17.6 million per MW all-in, and rents run from roughly $65 to $196 per kW-month.
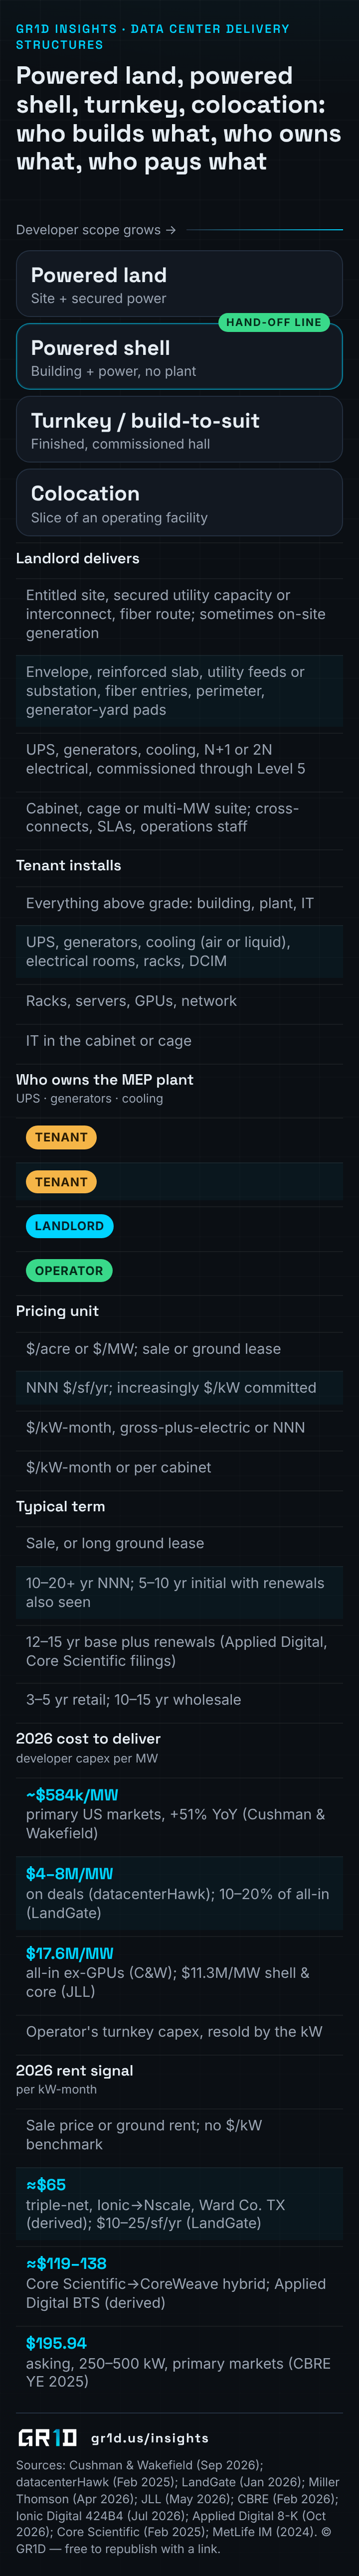
Read as text
- Powered land, powered shell, turnkey, colocation: who builds what, who owns what, who pays what
- Developer scope grows →
- Powered land
- Site + secured power
- Powered shell
- Building + power, no plant
- Turnkey / build-to-suit
- Finished, commissioned hall
- Colocation
- Slice of an operating facility
- Landlord delivers
- Entitled site, secured utility capacity or interconnect, fiber route; sometimes on-site generation
- Envelope, reinforced slab, utility feeds or substation, fiber entries, perimeter, generator-yard pads
- UPS, generators, cooling, N+1 or 2N electrical, commissioned through Level 5
- Cabinet, cage or multi-MW suite; cross-connects, SLAs, operations staff
- Tenant installs
- Everything above grade: building, plant, IT
- UPS, generators, cooling (air or liquid), electrical rooms, racks, DCIM
- Racks, servers, GPUs, network
- IT in the cabinet or cage
- Who owns the MEP plant · UPS · generators · cooling
- UPS · generators · cooling
- TENANT
- LANDLORD
- OPERATOR
- Pricing unit
- $/acre or $/MW; sale or ground lease
- NNN $/sf/yr; increasingly $/kW committed
- $/kW-month, gross-plus-electric or NNN
- $/kW-month or per cabinet
- Typical term
- Sale, or long ground lease
- 10–20+ yr NNN; 5–10 yr initial with renewals also seen
- 12–15 yr base plus renewals (Applied Digital, Core Scientific filings)
- 3–5 yr retail; 10–15 yr wholesale
- 2026 cost to deliver · developer capex per MW
- developer capex per MW
- ~$584k/MW · primary US markets, +51% YoY (Cushman & Wakefield)
- ~$584k/MW
- $4–8M/MW · on deals (datacenterHawk); 10–20% of all-in (LandGate)
- $4–8M/MW
- $17.6M/MW · all-in ex-GPUs (C&W); $11.3M/MW shell & core (JLL)
- $17.6M/MW
- Operator's turnkey capex, resold by the kW
- 2026 rent signal · per kW-month
- per kW-month
- Sale price or ground rent; no $/kW benchmark
- ≈$65 · triple-net, Ionic→Nscale, Ward Co. TX (derived); $10–25/sf/yr (LandGate)
- ≈$65
- ≈$119–138 · Core Scientific→CoreWeave hybrid; Applied Digital BTS (derived)
- ≈$119–138
- $195.94 · asking, 250–500 kW, primary markets (CBRE YE 2025)
- $195.94
What is a powered shell data center?
A powered shell is the building without the plant. The developer delivers the envelope, a slab and structure sized for data-hall loads, the utility feed or substation, fiber entries and a secured perimeter, usually with generator-yard pads and cooling pathways in place (Miller Thomson, Apr 2026; LandGate, Jan 2026). "UPS systems, backup generators, and cooling arrays" are omitted; the tenant installs them (LandGate).
That omission sets the economics. Shell tenants "install, maintain and own the long-lived and short-lived equipment," while a turnkey landlord owns the long-lived infrastructure and prices that risk into the rent; shell rent is quoted net per square foot, turnkey rent per kilowatt-month, gross plus electricity (MetLife IM, Jul 2024). The "warm shell" with switchgear or generators pre-installed has no authoritative 2026 definition; read the scope exhibit, not the label.
Powered land, powered shell, turnkey and colocation: who builds what?
The four products are stages of one build, walked through phase by phase in How a Data Center Is Built. Each hand-off moves capital and risk from developer to tenant.
| Layer | Landlord delivers | Tenant installs and owns | Pricing unit | Typical term |
|---|---|---|---|---|
| Powered land | Entitled site, secured utility capacity, fiber route; sometimes on-site generation | Everything above grade | $/acre or $/MW | Sale or ground lease |
| Powered shell | Envelope, reinforced slab, utility feeds or substation, fiber entries, generator-yard pads | UPS, generators, cooling, electrical rooms, racks | NNN $/sf/yr; increasingly $/kW committed | 10–20+ yr NNN; 5–10 yr initial also seen |
| Turnkey / build-to-suit | Fitted, commissioned hall; landlord owns the plant | Racks, servers, GPUs, network | $/kW-month | 12–15 yr base |
| Wholesale colocation | Multi-MW turnkey suites in an operating facility | IT | $/kW-month | 10–15 yr |
| Retail colocation | Cabinet or cage, cross-connects, SLAs | IT | $/kW-month or per cabinet | 3–5 yr |
Plant ownership is the line that matters: the tenant owns it in powered land and shell, the landlord or operator in turnkey and colocation, and the owner funds, commissions, maintains and eventually replaces it. No brokerage publishes the split between structures. Ares observes that "the U.S. market sees more powered-shell product" while dense, vertical markets skew turnkey (Ares, Aug 2026), and datacenterHawk counted roughly 100 of 130 tracked shell deals in Northern Virginia alone (datacenterHawk, Feb 2025); any percentage you see is an estimate.
How much does a powered shell cost per MW in 2026?
| Delivery stage | 2026 cost signal | Source |
|---|---|---|
| Powered land | ~$584,000 per MW, primary US markets, +51% YoY | Cushman & Wakefield, Sep 2026 |
| Powered shell, share basis | 10–20% of a finished facility; ~$1.8–3.5M per MW at $17.6M all-in (derived) | LandGate, Jan 2026 |
| Powered shell, deal basis | $4–8M per MW (turnkey $12–13M) | datacenterHawk, Feb 2025 |
| Shell and core | ~$11.3M per MW (2026 forecast), +47% since 2020 | JLL via Datacentres.com, May 2026 |
| Liquid cooling | +$1–2M per MW; AI-ready specification +15–25% | JLL via Datacentres.com, May 2026 |
| Greenfield turnkey, all-in ex-GPUs | ~$17.6M per MW, +21% since Q4 2024; power infrastructure ≈21% | Cushman & Wakefield, Sep 2026 |
| AI tenant fit-out | "can exceed $25M per MW" | JLL via Data Center Frontier, Jan 2026 |
The two shell numbers disagree about scope, not fact. LandGate's 10–20% is a share of a finished facility; against Cushman & Wakefield's $17.6M per MW it implies roughly $1.8–3.5M per MW (our derivation). datacenterHawk's $4–8M per MW comes from deals, where the shell increasingly includes the substation or utility upgrades and the generator-yard civil work that a share-of-building figure leaves out. Ask whether the substation and yard are inside any shell quote. The full stack is in our cost-per-MW guide.

Read as text
- What each stage costs to build, and what each structure rents for
- Left: developer capex per MW at each hand-off point. Right: what the tenant pays for that scope, from SEC-filed contract totals and CBRE asking rates; per-kW rents are derived, not quoted.
- Cost to deliver · $ million per MW · 0–25 scale · Powered land · $0.58M · Primary US markets, 2026 YTD, +51% YoY · Cushman & Wakefield, Sep 2026 · Powered shell, share basis 10–20% of a finished facility · $1.8–3.5M · LandGate share × C&W's $17.6M/MW all-in; excludes substation and yard · Powered shell, deal basis incl. substation, utility upgrades, gen yard · $4–8M · datacenterHawk, Feb 2025 (vs $12–13M/MW turnkey in the same source) · Shell & core, conventional air-cooled · $11.3M · JLL 2026 forecast, +6% YoY, +47% vs 2020; liquid cooling adds $1–2M/MW · Greenfield turnkey, all-in ex-GPUs · $17.6M · US & Canada average, +21% since Q4 2024 · Cushman & Wakefield, Sep 2026 · AI tenant fit-out
- Rent · $ per kW-month · 0–200 scale · Shell-type triple-net Ionic Digital → Nscale, Ward County, TX · ≈$65 · $182.5M/yr ÷ 234 MW ÷ 12 · 126-month NNN, 3% escalator after year 5; landlord builds nothing · 424B4, Jul 2026 · Hybrid Core Scientific → CoreWeave, Denton, TX · ≈$119 · $1.2B ÷ 12 yr ÷ 70 MW ÷ 12 · landlord funds $104M (~$1.5M/MW), tenant funds the rest · Feb 2025 · Turnkey build-to-suit Applied Digital, Delta Forge 2, AL · ≈$138 · $5.2B ÷ 15 yr ÷ 210 MW ÷ 12 · developer designs, builds, operates for an IG hyperscaler · 8-K, Oct 2026 · Colocation asking rate 250–500 kW, primary US markets · $195.94 · +6.5% YoY at year-end 2025; CBRE expects >$200 in 2026 · CBRE, Feb 2026 · 0 · 50 · 1
What does a powered shell lease look like?
A shell lease is triple-net: the tenant pays taxes, insurance and maintenance on top of base rent, terms run 10 to 20-plus years, and 2026 rents are $10–25 per square foot per year NNN (LandGate, Jan 2026). Miller Thomson sees 5–10 year initial terms with renewals, rent quoted per committed kilowatt, phased power with rent stepping up per tranche energized, and conditions precedent with long-stop dates (Miller Thomson, Apr 2026).
The best public example is in Texas. Ionic Digital's July 2026 prospectus discloses a 126-month triple-net lease to Nscale in Ward County: the landlord is "not responsible for construction or site development," the tenant pays taxes, insurance and maintenance, fixed rent is $182.5 million a year on 234 MW with a 3% escalator after year five, a further 89 MW is priced at the same rate, and the total is about $1.95 billion (Ionic Digital 424B4, Jul 2026). That is about $65 per kW-month (derived: $182.5M ÷ 234 MW ÷ 12). Because the landlord built nothing above grade, it sits at the powered-land end of the shell spectrum; a developer-built envelope should rent higher. We found no tenant-improvement benchmark tied to a named filing, so we quote none.
What do turnkey and build-to-suit leases cost per kW-month?
Turnkey rent is quoted per kilowatt-month and bundles the plant the landlord funded. Filings give three usable comps; the per-kW figures are derived from contract value, term and capacity.
| Deal | Structure | Term | Contract | Derived rent, $/kW-mo |
|---|---|---|---|---|
| Ionic Digital → Nscale, Ward County, TX | Triple-net; landlord builds nothing | 126 months | $182.5M/yr, 234 MW | $182.5M ÷ 234 ÷ 12 ≈ $65 |
| Core Scientific → CoreWeave, Denton, TX | Hybrid: landlord funds $104M (~$1.5M/MW), tenant the rest | 12 yr + 2×5 options | $1.2B, 70 MW | $1.2B ÷ 12 ÷ 70 ÷ 12 ≈ $119 |
| Applied Digital → IG hyperscaler, Delta Forge 2, AL | Turnkey build-to-suit; developer designs, builds, operates | 15 yr | $5.2B, 210 MW | $5.2B ÷ 15 ÷ 210 ÷ 12 ≈ $138 |
| CBRE asking rate, 250–500 kW, primary markets | Colocation | 3–5 yr typical | — | $195.94, +6.5% YoY |
Shell-type rent is roughly half of turnkey per kilowatt (65 ÷ 138 ≈ 47%; 65 ÷ 119 ≈ 55%); the gap is the plant the tenant funds instead. Denton sits in the middle because Core Scientific funded about $1.5M per MW of base infrastructure and CoreWeave the rest (Core Scientific, Feb 2025); Delta Forge 2 is the full product, designed, built and operated by Applied Digital for a "tier-one investment-grade hyperscaler" (Applied Digital, Oct 2026).
How do colocation rates compare?
Colocation tops the rent ladder because the price includes the operator's plant, staff and risk. CBRE's year-end 2025 asking rate for 250–500 kW requirements in primary markets was $195.94 per kW-month, up 6.5%, with 3–10 MW blocks up 12.5% and rates expected to pass $200 in 2026, against a record 1.4% vacancy (CBRE, Feb 2026); 74.3% of space under construction was preleased by mid-2025 (CBRE, Sep 2025). Texas is not one market: Houston carried 19.7% colocation vacancy in the first half of 2025 while Austin–San Antonio sat at 2.3% (CBRE, Sep 2025; CBRE Austin–San Antonio profile, 2025), so a 2 MW requirement is a buyer's market in one metro and a waiting list in the other. GR1D's colocation and GPU hosting is at /host.
How long does each take to deliver?
A powered shell takes 9–18 months, six to twelve for the shell plus three to six for tenant fit-out, against 18–36-plus months ground-up (LandGate, Jan 2026). A building "typically runs 18 to 24 months" from shell to commissioned (Construction Owners, Jul 2026), and land-to-power-on runs 18–36 months: permitting 6–24, construction 12–18, commissioning 2–6 (Global Data Center Hub, Nov 2025). This site plans on 18–30 months for a turnkey building.
Neither number includes the interconnect: a 100 MW grid connection in Northern Virginia averages seven years and the national average about four (JLL via Construction Owners, Jul 2026). In a shell deal the tenant's fit-out and the landlord's power run in parallel, and the lease has to say what happens when they fail to meet; see Realistic Data Center Timelines in 2026.
Who carries the risk when power slips?
Troutman's deal lawyers call delivery delay "the biggest commercial issue that's negotiated": hyperscale tenants ask for liquidated damages tied to rent plus a termination right, lenders object to the termination right because it can zero the collateral, and developers push for carve-outs excusing utility-caused delay (Troutman, Dec 2025). The drafting tools are phased delivery with rent per MW energized, conditions precedent and long-stop dates (Miller Thomson, Apr 2026). Ionic–Nscale shows the expansion variant: "no penalty" if the additional 89 MW is not delivered, so the expansion is an option, not an obligation (Ionic Digital 424B4, Jul 2026). Commissioning follows ownership: in a shell the landlord proves the feed and substation and the tenant commissions its own plant; in turnkey the landlord delivers Level 5 and an SLA, though hyperscalers "often bring their own commissioning teams" either way (Global Data Center Hub, Nov 2025).

Read as text
- Who carries each risk: powered shell, turnkey or colocation
- Who funds each exposure in a typical 2026 lease, and the mechanism that moves it. Ownership of the MEP plant decides most cells.
- TENANT
- LANDLORD
- OPERATOR
- SPLIT
- Superscripts refer to the footnotes.
- Powered shell · Tenant owns the plant
- Tenant owns the plant
- Turnkey / build-to-suit · Landlord owns the plant
- Landlord owns the plant
- Colocation · Operator owns the facility
- Operator owns the facility
- Power delay · utility feed, interconnect, energization
- utility feed, interconnect, energization
- LANDLORDDelivers the feed. Tenants seek rent-tied LDs plus a termination right; developers seek utility-delay carve-outs.1
- LANDLORDSame mechanics; rent starts at commissioning, so a slip hits landlord revenue first. Phased rent per MW energized is the compromise.1, 2
- 1, 2
- OPERATORCapacity exists before signing; delay risk sits only on expansion phases.
- Construction cost & procurement · UPS, generators, cooling, switchgear
- UPS, generators, cooling, switchgear
- TENANTFunds and procures the plant and carries transformer and switchgear lead times.
- LANDLORDCarries ~$17.6M/MW all-in and the equipment calendar, priced into a rent about double the shell rate per kW.
- OPERATORSunk on the operator's balance sheet; tenant pays by the kW with no capex.
- Commissioning · Levels 1–5, acceptance
- Levels 1–5, acceptance
- SPLITLandlord proves the utility feed and substation; tenant commissions the plant it installed.
- LANDLORDDelivers Level 5 and an SLA; hyperscalers "often bring their own commissioning teams" to witness it.
- OPERATOROperator; the tenant relies on the SLA and the acceptance test.
- Obsolescence & density · GB300 142 kW → Vera Rubin 190–230 kW per rack
- GB300 142 kW → Vera Rubin 190–230 kW per rack
- TENANTOwns the plant, so chooses liquid loops and density and pays for each refresh; the building itself ages slowly.
- LANDLORDOwns the long-lived infrastructure and its refresh; a density mismatch at renewal is the landlord's problem.
- OPERATORTenants get the density on offer; 250–500 kW colo blocks rarely stretch to AI rack loads.
- Re-leasing · rollover, tenant credit
- rollover, tenant credit
- LANDLORDLow-obsolescence building, but re-leasability is tied to one tenant's fit-out.
- LANDLORDTenant-credit concentration; a dropped BTS can be re-let, as Abilene was to Microsoft in Mar 2026.
- OPERATORChurn, offset by mark-to-market on every rollover at rising asking rates.
- Operating · taxes, insurance, maintenance, power
- taxes, insurance, maintenance, power
- TENANTTriple-net: tenant pays taxes, insurance and maintenance and buys power directly.3
- SPLITLandlord maintains the plant; tenant pays power as a pass-through, gross-plus-electric or NNN.
- OPERATOROperator runs it; tenant pays $/kW-month with power included or passed through.
- 1Troutman, Dec 2025: delivery delay is "the biggest commercial issue that's negotiated." Hyperscalers seek LDs tied to rent plus a termination right; lenders object to the termination right; developers seek utility-delay carve-outs.
- 2Miller Thomson, Apr 2026: phased power with rent stepping up per MW energized; conditions precedent and long-stop dates if the utility is late. Ionic–Nscale, Jul 2026: "no penalty" if the 89 MW expansion is not delivered.
- 3Ionic Digital 424B4, Jul 2026: 126-month triple-net; landlord "not responsible for construction or site development"; tenant pays taxes, insurance and maintenance; 3% escalator after year 5. MetLife IM, 2024: shell tenants "install, maintain and own" the equipment.
Which structure do AI tenants choose?
Density decides it. A GB300 NVL72 rack draws up to 142 kW, Vera Rubin NVL72 is specified at 190–230 kW, the Kyber generation due in late 2027 approaches 600 kW, air cooling is impractical above about 50 kW per rack and direct-to-chip liquid is the working answer at 100–150 kW (Data Center Knowledge, Aug 2026). JLL describes training at "40 kW per rack and well beyond," a preference for single-tenant leases and AI-optimized rents "up to 60% higher" than traditional space (JLL via Data Center Frontier, Jan 2026). Colocation's $195.94 benchmark covers 250–500 kW blocks at conventional densities, a different product.
That leaves two choices. Take the shell when you have your own electrical and liquid-cooling standard and the balance sheet to fund the plant; you then control density, refresh and the coolant loop, as CoreWeave does at Denton. Take build-to-suit when you want the landlord to carry the plant and its refresh and will pay about double the shell rent per kilowatt, as Applied Digital's hyperscaler does. Either way the building is designed for liquid from the slab up; see Liquid Cooling for GPU Data Centers.
Pros and cons from both sides of the table
| Structure | Tenant view | Developer view |
|---|---|---|
| Powered shell | For: control of density and liquid cooling, lower rent per kW, own the plant. Against: funding and owning the plant, procurement risk, equipment lead times. | For: low capex per MW, fast to revenue, low obsolescence. Against: one tenant sets the price; re-leasing depends on its fit-out. |
| Turnkey / build-to-suit | For: speed to operate, landlord carries refresh, SLA. Against: higher rent per kW, less control, longer build. | For: higher rent per kW. Against: $17.6M per MW capex, obsolescence, tenant-credit concentration. |
| Colocation | For: minimal capex, short terms, fast. Against: limited density, asking rates near $196 per kW-month. | For: mark-to-market on every rollover. Against: operating cost, staffing, churn. |
What do shell, turnkey and colocation look like in Texas?
Every rung has a dated Texas example. Powered land: Calpine and CyrusOne's 400 MW agreement at the Thad Hill Energy Center in Bosque County, Calpine supplying "power, grid connection, and land," operating from the fourth quarter of 2026 (Calpine, Nov 3, 2025). Powered shell: Harrison Street and PowerHouse's 200 MW Irving–Las Colinas campus, three shells and 946,000 sq ft on 50 acres in Oncor territory (IREI, May 16, 2024), and Ionic Digital's Ward County site leased to Nscale, 234 MW energized and a 700 MW target by end-2027 (Ionic Digital 424B4, Jul 2026). Hybrid: Core Scientific's Denton campus, about 260 MW for CoreWeave after the 70 MW, $1.2 billion expansion of February 26, 2025 (Core Scientific, Feb 2025). Build-to-suit: in Abilene, Microsoft agreed in March 2026 to rent a roughly 700 MW Crusoe-developed project that Oracle and OpenAI had dropped (Bloomberg Government, Mar 24, 2026). Colocation: TRG's HOU2 in Spring, 24 MW and 110,000 sq ft, due in the fourth quarter of 2026 (TRG Datacenters, Nov 2025).
The markets diverge. Dallas–Fort Worth absorbed 470.8 MW net in 2025, up 424 MW on the year (CBRE, Feb 2026); Austin–San Antonio had 462 MW under construction at mid-2025, 97% preleased, with developers targeting northeast Austin in Oncor territory and LCRA territory to the south (CBRE Austin–San Antonio profile, 2025). Houston's 19.7% colocation vacancy is the exception, which is why product there is built for a named tenant rather than on spec.
Frequently asked questions
What does the landlord deliver in a powered shell data center?
The envelope, a slab and structure rated for data-hall loads, the utility feed or substation, fiber entries and usually generator-yard pads. The tenant installs and owns the UPS, generators, cooling and racks (LandGate, Jan 2026; Miller Thomson, Apr 2026).
How much does a powered shell cost per MW?
About $4–8M per MW on a deal basis (datacenterHawk), or 10–20% of a finished facility (LandGate), about $1.8–3.5M per MW at Cushman & Wakefield's $17.6M all-in. The gap is whether the substation and generator yard are in scope.
What is the difference between powered shell and turnkey?
Who owns the plant. A shell tenant funds, installs, commissions and owns the UPS, generators and cooling and pays net rent; a turnkey landlord owns the plant, commissions it to Level 5 and charges per kW-month, about double the shell rent in 2026 comps.
What is a NNN data center lease?
A triple-net lease: the tenant pays property taxes, insurance and maintenance on top of base rent. Ionic Digital's 126-month lease to Nscale in Ward County is one, with a 3% escalator from year six.
How long does a powered shell take to build?
Six to twelve months once sitework is done, plus three to six months of tenant fit-out: 9–18 months in total, against 18–36-plus months ground-up (LandGate). Neither includes the grid interconnection, which averages about four years.
Which structure do AI tenants prefer?
Single-tenant shell or build-to-suit buildings designed for 100–150 kW liquid-cooled racks: shell for tenants with their own electrical and cooling standards who fund the plant, build-to-suit for those who want the landlord to own and refresh it.
Sources
- Powered shell data centers: everything you need to know — LandGate, 2026-01-10
- Between dirt and data centres: why the powered shell model is gaining traction — Miller Thomson, 2026-04-16
- The future of data centers: trends, challenges and opportunities — MetLife Investment Management, 2024-07-23
- Understanding powered shell data centers — datacenterHawk, 2025-02-19
- What are the different types of data center infrastructure? — Ares Management, 2026-08-25
- Cushman & Wakefield releases 2026 Data Center Development Cost Guide — Cushman & Wakefield via Business Wire, 2026-09-03
- Data centre construction costs reach $11.3M per MW — Datacentres.com (JLL data), 2026-05-12
- JLL's 2026 Global Data Center Outlook: navigating the AI supercycle — Data Center Frontier (JLL data), 2026-01-08
- North America Data Center Trends H2 2025 — CBRE, 2026-02-25
- North America Data Center Trends H1 2025 — CBRE, 2025-09-08
- North America Data Center Trends H1 2025: Austin–San Antonio market profile — CBRE, 2025-09
- Ionic Digital prospectus (Form 424B4) — Ionic Digital via SEC EDGAR, 2026-07
- Applied Digital fiscal Q1 2027 earnings release (Form 8-K exhibit) — Applied Digital via SEC EDGAR, 2026-10-07
- Core Scientific expands CoreWeave contract at Denton — Core Scientific, 2025-02-26
- How long it actually takes to power a data center in 2026 — Construction Owners Association of America, 2026-07-01
- From permit to power-on: how data centers get built — Global Data Center Hub, 2025-11-21
- How energy scarcity is changing data center deals — Troutman Pepper Locke, 2025-12-04
- AI rack density's real limits: power, cooling, failure risk — Data Center Knowledge, 2026-08-28
- Harrison Street and PowerHouse JV enters Dallas–Fort Worth market with 200 MW campus — IREI, 2024-05-16
- Calpine and CyrusOne announce Phase 2 of powered land agreement at Thad Hill Energy Center — Calpine, 2025-11-03
- Microsoft to rent Texas data center dropped by Oracle, OpenAI — Bloomberg Government, 2026-03-24
- TRG Datacenters 24 MW expansion (HOU2) — TRG Datacenters, 2025-11-18
- Batch Zero Update — ERCOT, 2026-09-11
- Texas Large Load Interconnection Update: ERCOT Batch Zero Pause and Verification Process — Baker Botts, 2026-08
- PUCT sets financial commitments for data center interconnection; Governor pauses permits — White & Case, 2026-09-25
- Texas pauses all environmental permitting for data centers — Beveridge & Diamond, 2026-09-29
Building or financing an AI data center in Texas?
GR1D develops powered-shell and turnkey AI data centers — 20 MW to 150 MW sites with power, fiber and entitlements solved before the first rack arrives. See how we build, browse our sites or talk to us.