What It Costs to Build a Data Center in 2026: Land, Power, Shell and Fit-Out per MW
A greenfield data center costs about $17.6 million per MW to build in 2026, all-in and before GPUs, inside a range of $8.9 million to $23.3 million. Shell and core alone runs about $11.3 million per MW, and Texas builds come in between $9 million and $16 million. GPUs and servers add another $29 million to $42 million per MW on top. Which figure applies depends on three things this guide separates: what the megawatt measures, where the developer stops, and which market you build in.
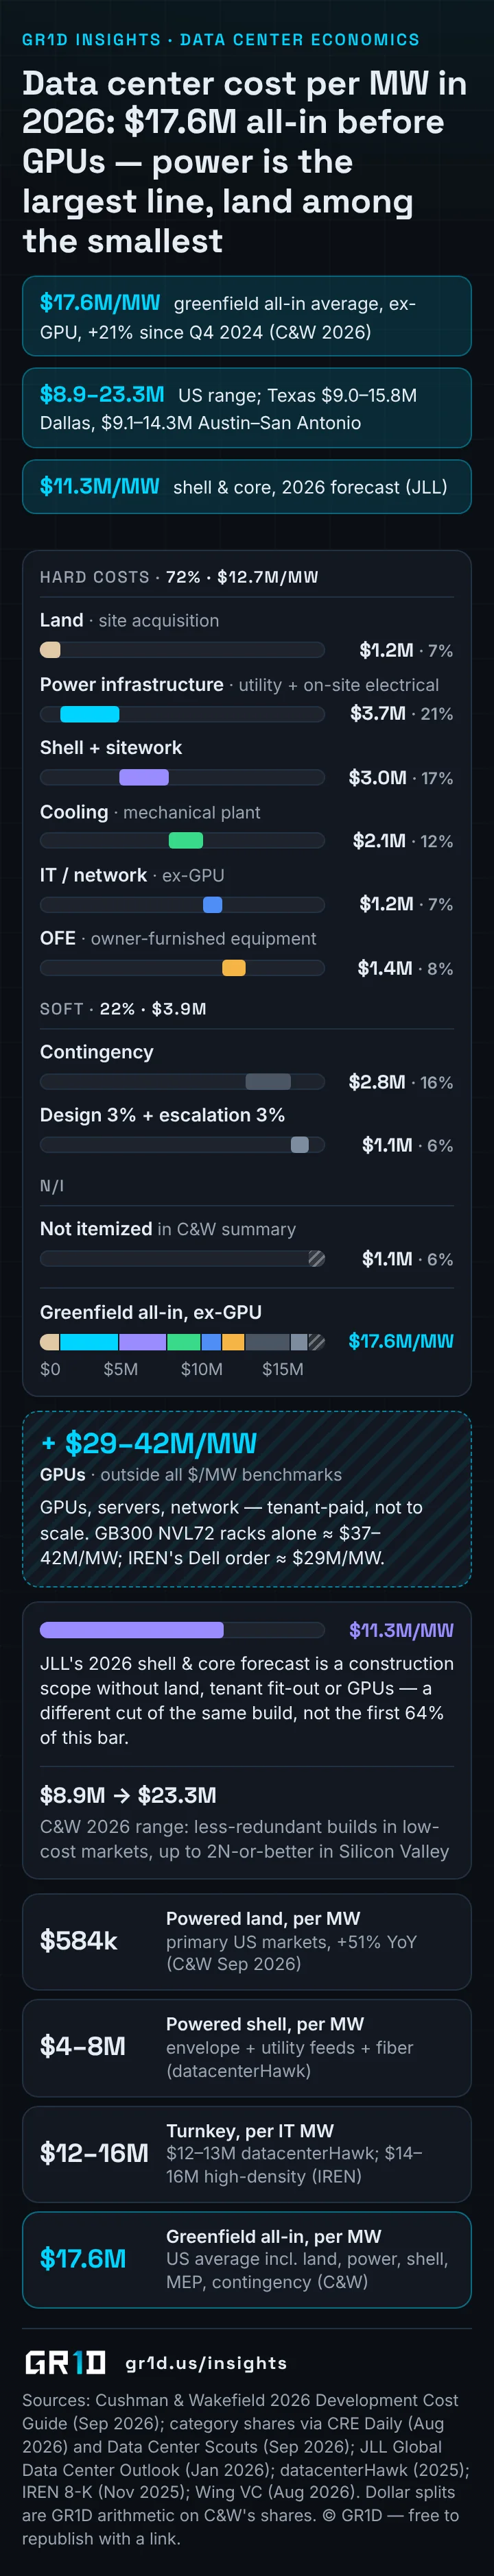
Read as text
- Data center cost per MW in 2026: $17.6M all-in before GPUs — power is the largest line, land among the smallest
- $17.6M/MW greenfield all-in average, ex-GPU, +21% since Q4 2024 (C&W 2026)
- $8.9–23.3M US range; Texas $9.0–15.8M Dallas, $9.1–14.3M Austin–San Antonio
- $11.3M/MW shell & core, 2026 forecast (JLL)
- HARD COSTS · 72% · $12.7M/MW
- Land · site acquisition · $1.2M · 7%
- Power infrastructure · utility + on-site electrical · $3.7M · 21%
- Shell + sitework · $3.0M · 17%
- Cooling · mechanical plant · $2.1M · 12%
- IT / network · ex-GPU · $1.2M · 7%
- OFE · owner-furnished equipment · $1.4M · 8%
- SOFT · 22% · $3.9M
- Contingency · $2.8M · 16%
- Design 3% + escalation 3% · $1.1M · 6%
- N/I
- Not itemized in C&W summary · $1.1M · 6%
- Greenfield all-in, ex-GPU · $17.6M/MW
- $0 · $5M · $10M · $15M
- $0
- $5M
- $10M
- $15M
- + $29–42M/MW · GPUs · outside all $/MW benchmarks · GPUs, servers, network — tenant-paid, not to scale. GB300 NVL72 racks alone ≈ $37–42M/MW; IREN's Dell order ≈ $29M/MW.
- $11.3M/MW · JLL's 2026 shell & core forecast is a construction scope without land, tenant fit-out or GPUs — a different cut of the same build, not the first 64% of this bar.
- $8.9M → $23.3M · C&W 2026 range: less-redundant builds in low-cost markets, up to 2N-or-better in Silicon Valley
- $584k · Powered land, per MW · primary US markets, +51% YoY (C&W Sep 2026)
- $4–8M · Powered shell, per MW · envelope + utility feeds + fiber (datacenterHawk)
- $12–16M · Turnkey, per IT MW · $12–13M datacenterHawk; $14–16M high-density (IREN)
- $17.6M · Greenfield all-in, per MW · US average incl. land, power, shell, MEP, contingency (C&W)
Why are "$11 million per MW" and "$17.6 million per MW" both correct?
Every page that ranks for this query quotes one blended number, and the common ones are all right for different scopes. JLL tracks shell and core — $7.7M per MW in 2020, $10.7M in 2025, a forecast $11.3M in 2026 — with AI fit-out of "as much as $25 million per MW" paid by the tenant (JLL, Jan 2026). Cushman & Wakefield measures the whole project excluding chips at $17.6M per MW (Cushman & Wakefield, Sep 2026), from $8.9M for a less-redundant build in a low-cost market to $23.3M for "fully redundant 2N or better" (CRE Daily, Aug 2026). Turner & Townsend counts construction only, for a 30–50 MW air-cooled hall: Silicon Valley $13.3 per watt (Turner & Townsend, Nov 2025), Dallas $9.5M per MW (via Data Center Scouts, Sep 2026).
| Benchmark | 2026 figure | What it covers |
|---|---|---|
| JLL Global Data Center Outlook | $11.3M per MW (2026F), from $7.7M in 2020 | Shell and core; excludes tenant fit-out and GPUs |
| Cushman & Wakefield Cost Guide | $17.6M per MW average; $8.9–23.3M range | All-in greenfield: land, power, shell, MEP, contingency; excludes GPUs |
| Turner & Townsend Cost Index | Dallas $9.5M to Silicon Valley $13.3M per MW | Construction only, 30–50 MW air-cooled; excludes land, utility, site works |
| IREN Horizon, Texas | $14–16M per IT MW | Tier III-equivalent liquid-cooled facility; excludes GPUs |
IT MW, gross MW or MW with GPUs: which megawatt is being quoted?
Critical IT MW is the load available to racks and the number tenants pay for. Gross MW is what the utility sees: IT load times PUE, so at PUE 1.25 a 20 MW IT hall draws about 25 MW and a 60 MW IT hall about 75 MW. Core Scientific's disclosures show the gap at scale: roughly 590 MW of infrastructure is about 800 MW gross (Core Scientific, Jul 2026). The gross figure matters in Texas because ERCOT's 75 MW large-load threshold applies to requested demand, not IT load, so PUE decides which side of the line a 60 MW IT hall lands on.
The third megawatt has chips in it: $14–16M per MW without GPUs becomes roughly $43–45M with them (derived from IREN, Nov 2025).
What does the 2026 cost stack look like by delivery stage?
Cushman & Wakefield publishes the split behind its $17.6M average, with power infrastructure "the single largest cost" at 21% (CRE Daily, Aug 2026; Data Center Scouts, Sep 2026). The published shares sum to 94%; the rest is not itemized.
| Category | Share | $ per MW (derived) |
|---|---|---|
| Power infrastructure (interconnect, substation, on-site electrical) | 21% | ~$3.7M |
| Core and shell plus sitework | 17% | ~$3.0M |
| Contingency | 16% | ~$2.8M |
| Cooling | 12% | ~$2.1M |
| Owner-furnished equipment | 8% | ~$1.4M |
| IT and network, excluding GPUs | 7% | ~$1.2M |
| Site acquisition | 7% | ~$1.2M |
| Design 3%, escalation 3% | 6% | ~$1.1M |
| Not itemized in the public summary | 6% | ~$1.1M |
Land. Powered land in primary US markets averages $584,000 per MW, up 51% year over year (Cushman & Wakefield, Sep 2026), and is still only about 7% of the stack. Rural Texas runs far lower: Crusoe's Haskell County campus is 2,042 acres under a roughly $1 billion first phase (Haskell County, Jul 2026).
Power. No 2026 guide publishes a substation cost per MW; the 21% share, about $3.7M, is the best proxy. Lead time is the hidden cost: pad-mount transformers 68–113 weeks, generators 60–100, medium-voltage switchgear 38–63 (CRE Daily, Aug 2026).
Powered shell. datacenterHawk prices a powered shell at $4–8M per MW against $12–13M turnkey; the shell is 14% of an air-cooled build's construction cost and 9% of a liquid-cooled one (datacenterHawk and Turner & Townsend via Data Center Scouts). The scopes are compared in Powered Shell vs Turnkey vs Colocation.
MEP fit-out and turnkey. IREN's filing is the most specific public figure: $9–11M per IT MW for Tier III-equivalent infrastructure at 130–200 kW per rack, plus $3M per MW for a 100 MW supercluster architecture (IREN, Nov 2025).
IT. A GB300 NVL72 rack is "just under $5.0M" on purchase orders and about $5.7M deployed, at 132–140 kW (Wing VC, Aug 2026); at about 7.4 racks per IT MW that is $37–42M per MW for racks alone (derived). IREN's $5.8B Dell order for about 200 MW is about $29M per MW including servers, InfiniBand, cabling and software (IREN, Nov 2025).
Soft costs. Contingency 16%, design 3%, escalation 3%. No published 2026 benchmark exists for developer fees or prefabricated cost per MW, so both are left out.
What does Texas add to, or take off, the per-MW number?
Interconnection security. Under PUCT rule 16 TAC §25.194, adopted September 18, 2026 and effective October 8, a load of 75 MW or more pays a $100,000 study fee and posts $50,000 per MW of requested peak demand before study; at the interconnection agreement it becomes the greater of that or the allocated transmission upgrade cost, refunded 20% at energization and the rest in tranches, and utilities invoice direct interconnection costs (CIAC) up front (White & Case, Sep 2026). For a 75 MW request that is $3.75M posted. The mechanics are in ERCOT Large-Load Interconnection in Texas.
Abatements. Crusoe's Haskell County agreement grants a 100% county abatement for ten years per phase with a payment in lieu of taxes of the greater of $10M a year or 25% of taxes (Haskell County, Jul 2026). The state sales-tax exemption ($200M invested, 100,000 square feet, 20 jobs) is projected to cost $3.3B in 2028–29 and lawmakers questioned it in July (Texas Public Radio, Jul 2026); underwrite equipment with and without it.
Power price. Cushman & Wakefield rates Texas "among the lowest-cost development environments" (via Data Center Scouts), and operating cost widens the gap. EIA forecast ERCOT wholesale power near $30 per MWh for 2025 against a $40 national composite (EIA, Jan 2025). One IT MW at PUE 1.2 uses about 10,512 MWh a year: about $0.63M per MW-year at $60 per MWh all-in, against $0.92M at the US industrial rate of 8.71 cents per kWh (EIA via Metro Colo Advisory, 2026; derived). On-site generation buys time, not cheaper energy: $101–107 per MWh delivered against about $86 from the grid (Rabobank, Jun 2026).
How much does a 20 MW powered shell cost?
datacenterHawk's $4–8M per MW applied to a 20 MW IT powered shell in a Texas secondary market gives $80–160M. The split is a GR1D illustration, not a quote: the power line scales C&W's 21% share to a shell scope and soft costs are shown separately so the columns add up.
| Line item | 20 MW IT powered shell | Basis |
|---|---|---|
| Land and site acquisition | $4–8M | Rural Texas |
| Utility interconnection, substation, MV switchgear | $25–45M | C&W power share scaled to shell scope (assumption) |
| Building, sitework, fiber entries, generator pads | $39–82M | Structure rated for racks above 3,000 lb |
| Design, contingency, escalation | $12–25M | ~15% of the shell budget |
| Total | $80–160M ($4–8M per IT MW) | datacenterHawk via Data Center Scouts |
The tenant then spends far more than the developer: $9–11M per MW of MEP fit-out ($180–220M) and about $29M per MW of IT ($580M) on IREN's figures. The shell is a tenth to a sixth of the tenant's outlay.
How much does a 60 MW turnkey AI data center cost?
A 60 MW IT liquid-cooled turnkey facility in Texas at $13–16M per MW — the top of C&W's Dallas range (up to $15.8M) and IREN's $14–16M — comes to $780–960M before GPUs; the 6% C&W does not itemize is folded into the electrical line.
| Line item | 60 MW IT turnkey, liquid-cooled | Share |
|---|---|---|
| Land and site acquisition | $55–67M | 7% |
| Power infrastructure | $164–202M | 21% |
| Core and shell plus sitework | $133–163M | 17% |
| Cooling (liquid loop, CDUs, heat rejection) | $94–115M | 12% |
| Electrical, owner-furnished equipment, IT and network ex-GPU | $164–202M | 21% |
| Design, contingency, escalation | $172–211M | 22% |
| Total ex-GPU | $780–960M ($13–16M per IT MW) | |
| GPUs, servers, network at $29–42M per MW | $1.74–2.5B | |
| All-in with GPUs | $2.5–3.5B | building ≈ 30% |
Gross draw at PUE 1.25 is about 75 MW, which puts the facility at the §25.194 line: the $100,000 fee plus about $3.75M of security. At PUE 1.2 the same hall draws 72 MW. That is a design decision with a regulatory consequence, and one reason the schedule math for a 60 MW IT block in Texas starts with the cooling design.

Read as text
- A 20 MW powered shell is an $80–160M project; a 60 MW turnkey AI facility is $780–960M before GPUs
- GR1D arithmetic on published inputs — datacenterHawk $4–8M/MW shell, C&W Dallas and IREN $13–16M/MW turnkey, C&W 2026 category shares, PUE 1.25. Columns show each budget's midpoint split; tables show the ranges.
- A · 20 MW IT powered shell · Texas secondary market · developer scope ends at the envelope, utility feeds and fiber · $80–160M · $4–8M PER IT MW · 29% · 50% · 16% · midpoint split of $120M · Land · rural Texas, below the $584k/MW primary-market powered-land price · $4–8M ≈5% · Utility interconnection, substation, MV switchgear · C&W power share scaled to shell scope — assumption · $25–45M ≈29% · Building, sitework, fiber entries, generator pads · structure rated for 3,000 lb+ racks · $39–82M ≈50% · Design, contingency, escalation · ~15% of the shell budget · $12–25M ≈16% · UNDER THE LINE · Gross draw ≈ 25 MW at PUE 1.25 — not an ERCOT large load; no $100k study fee, no $50k/MW security. · TE
- Land · rural Texas, below the $584k/MW primary-market powered-land price · $4–8M ≈5%
- Utility interconnection, substation, MV switchgear · C&W power share scaled to shell scope — assumption · $25–45M ≈29%
- Building, sitework, fiber entries, generator pads · structure rated for 3,000 lb+ racks · $39–82M ≈50%
- Design, contingency, escalation · ~15% of the shell budget · $12–25M ≈16%
- B · 60 MW IT turnkey, liquid-cooled · Texas · delivered with switchgear, UPS, generators and cooling commissioned · $780–960M · $13–16M PER IT MW, EX-GPU · 21% · 17% · 12% · 21% · 22% · midpoint split of $870M · Land / site acquisition $55–67M 7% · Power infrastructure · utility interconnect, substation, on-site electrical · $164–202M 21% · Core & shell + sitework $133–163M 17% · Cooling · liquid loop, CDUs, heat rejection · $94–115M 12% · Electrical, OFE, IT/network ex-GPU · incl. the 6% C&W does not itemize · $164–202M 21% · Design, contingency, escalation $172–211M 22% · AT THE LINE · Gross ≈ 75 MW at PUE 1.25 → PUCT §25.194 applies: $100k fee + ~$3.75M security. At PUE 1.2 the same hall
- Land / site acquisition $55–67M 7%
- Power infrastructure · utility interconnect, substation, on-site electrical · $164–202M 21%
- Core & shell + sitework $133–163M 17%
- Cooling · liquid loop, CDUs, heat rejection · $94–115M 12%
- Electrical, OFE, IT/network ex-GPU · incl. the 6% C&W does not itemize · $164–202M 21%
- Design, contingency, escalation $172–211M 22%
- SAME BUDGETS DRAWN TO SCALE (MIDPOINTS)
- $80–160MA · 20 MW shell
- $80–160M
- $780–960MB · 60 MW turnkey, ex-GPU
- $780–960M
- $2.5–3.5BB with GPUs
- $2.5–3.5B
What moves the number up or down?
- Density and liquid cooling. A 7–10% premium at equal IT capacity (Turner & Townsend, Nov 2025), with the mechanical share rising from 22% to 33% (via Data Center Scouts). A liquid retrofit of a mining site is about $2M per MW (Measured AI, Apr 2026).
- Redundancy. Most of C&W's $8.9M-to-$23.3M spread is redundancy and market; 2N tops it, and AI training halls "often need less redundancy" (Turner & Townsend via Data Center Scouts).
- Labor market. Dallas $9.5M, Northern Virginia $10.9M and Silicon Valley $13.3M per MW in the T&T index; MEP wages rose about 5% a year from 2021 to 2024 (CRE Daily, Aug 2026).
- Equipment inflation and tariffs. Since December 2021, switchgear is up 60%, copper 46%, generators 33%, cooling equipment 32% and transformers 29% (CRE Daily, Aug 2026); nonresidential costs rose 6.77% year over year in Q1 2026, with structural steel up 3.8% in the quarter on tariff exposure (Mortenson, 2026).
- Cost of capital. Core Scientific sold $3.3B of 7.75% senior secured notes due 2031 in May 2026 (Cahill, May 2026); spreads are widening (Rittenhouse Research, Sep 2026).
- Delay. Lost rent runs about $155,000 per MW-month: Hut 8's two 15-year Beacon Point leases, $19.6B over 704 MW of IT, work out to $1.9M per MW-year (btw.media, Jul 2026); the tenant is undisclosed, though the Financial Times reported it is NVIDIA (Crypto Briefing, Jul 2026). Add carry of about $77,000 (7.75% on $12M per MW) and delay costs about $0.23M per MW per month (derived), or $14M a month on 60 MW. IREN's $2M per MW acceleration payment is the market price of avoiding it.
- Scale. The evidence is thin: T&T prices a 30–50 MW hall, C&W's range is by market and redundancy, and no guide prices sub-5 MW builds.

Read as text
- Dallas builds for $9.5M per MW; Silicon Valley for $13.3M. Equipment inflation moved every market
- Left: construction cost only for a 30–50 MW air-cooled hyperscale facility (excludes land, utility and site works). Right: all-in development cost ranges, ex-GPU, with the US average marked.
- Construction cost per MW, Turner & Townsend 2025–26 · $M per MW; Dallas and Charlotte are the lowest-cost US markets in the index · Dallas · $9.5M · Charlotte · $9.5M · Phoenix · $9.8M · Atlanta · $9.9M · N. Virginia · $10.9M · Portland · $10.9M · Chicago · $11.2M · Silicon Valley · $13.3M · $0 · $2M · $4M · $6M · $8M · $10M · $12M · $14M
- All-in development cost range per MW, Cushman & Wakefield 2026 · $M per MW, ex-GPU; low end = less redundancy, high end = 2N or better. Chart readings ±$0.2M. · Austin–San Antonio · $9.1–14.3M · Dallas · $9.0–15.8M · N. Virginia · $9.4–17.6M · Phoenix · $10.2–17.0M · Silicon Valley · $14.0–23.3M · $0 · $4M · $8M · $12M · $16M · $20M · $24M · ▍ US greenfield average $17.6M/MW, +21% since Q4 2024. Both Texas markets top out below it; C&W calls Texas "among the lowest-cost development environments."
- EQUIPMENT PRICES SINCE DECEMBER 2021 (C&W 2026) — AND THE INFLATION THAT SITS ON TOP
- +60% · switchgear
- +60%
- switchgear
- +46% · copper
- +46%
- copper
- +33% · generators
- +33%
- generators
- +32% · cooling equipment
- +32%
- cooling equipment
- +29% · transformers
- +29%
- transformers
- +5%/yr · MEP wages 2021–24 (C&W)
- +5%/yr
- MEP wages 2021–24 (C&W)
- +6.77% · nonresidential costs YoY, Q1 2026 (Mortenson)
- +6.77%
- nonresidential costs YoY, Q1 2026 (Mortenson)
- +7–10% · liquid-cooled AI premium at equal IT capacity (T&T)
- +7–10%
- liquid-cooled AI premium at equal IT capacity (T&T)
What have developers actually disclosed per MW?
Filings and lease terms beat cost guides because someone signed them.
| Project | $ per MW | Scope and source |
|---|---|---|
| IREN Horizon 1–4, Childress, TX | $14–16M per IT MW | $9–11M infrastructure + $3M supercluster + $2M acceleration (IREN 8-K, Nov 2025) |
| Cipher–Amazon, Stingray, TX | Tenant funds capex above $10.5M | Turnkey ex-IT cap (Rittenhouse, Sep 2026) |
| Core Scientific, CoreWeave sites | $11–12M average buildout capex | ~590 MW infrastructure, ~800 MW gross (Core Scientific, Jul 2026) |
| Riot Rockdale, TX | $3.6M | Mining-site conversion, ex-IT (Measured AI, Apr 2026) |
| Hut 8 Beacon Point, TX | ~$12.6M per IT MW (derived) | 704 MW IT, $19.6B of 15-year leases (Rittenhouse, Sep 2026; btw.media, Jul 2026) |
| Stargate Abilene, TX | ~$12.5M per gross MW (derived) | $15B over 1.2 GW gross (DCD, Nov 2025); ~0.3 GW operating by April 2026 (Epoch AI, Apr 2026) |
The disclosed numbers cluster: greenfield turnkey at $10.5–16M per IT MW, conversions at $3.6–12M, and GPUs at roughly twice the building.
Is it cheaper to build or lease at these numbers?
Colocation for a 250–500 kW requirement in primary markets averaged $195.94 per kW per month at the end of 2025, up 6.5% year over year, with vacancy at a record 1.4% (CBRE, Feb 2026); more than 80% of the 7,481 MW under construction is preleased (CBRE, Aug 2026). Hyperscale triple-net rent implied by Hut 8's Beacon Point leases is about $150–160 per kW per month, or $1.9M per MW-year (derived).
Building wins when the tenant must control density, cooling and schedule at 20 MW or more; leasing wins below about 10 MW or when the load must be live within a year. At 1.4% vacancy the choice is often between a build you control and a lease you cannot find.
Frequently asked questions
How much does it cost to build a data center per MW in 2026?
About $17.6M per MW all-in for a US greenfield build before GPUs, inside a range of $8.9–23.3M (Cushman & Wakefield). Shell and core alone is about $11.3M per MW (JLL). Texas runs $9.0–15.8M in Dallas and $9.1–14.3M in Austin–San Antonio.
Does the cost per MW include GPUs?
Almost never. JLL, Cushman & Wakefield and Turner & Townsend all exclude chips. GPUs, servers and networking add roughly $29–42M per IT MW: IREN's Dell order works out to about $29M per MW, and GB300 NVL72 racks alone are $37–42M per MW.
How much does a 20 MW data center cost?
As a powered shell, about $80–160M at $4–8M per MW (datacenterHawk). As a turnkey facility, roughly $260–320M at $13–16M per MW. With GPUs at about $29M per MW more, a 20 MW AI facility passes $800M all-in.
Why is Texas cheaper per MW than Northern Virginia?
Labor, land and power. Turner & Townsend puts Dallas at $9.5M per MW of construction against $10.9M in Northern Virginia; RSMeans prices Austin and Dallas at $397.80 per square foot against $688.26 in Palo Alto; and EIA forecast ERCOT wholesale power near $30 per MWh in 2025 against a $40 national composite.
What does the PUCT $50,000 per MW security cover, and is it refundable?
Under 16 TAC §25.194 a load of 75 MW or more posts $50,000 per MW of requested demand before study, plus a $100,000 fee. At the interconnection agreement the security becomes the greater of that amount or the allocated transmission upgrade cost; 20% is returned at energization and the balance in 20% tranches (White & Case).
Sources
- 2026 Global Data Center Outlook — JLL, 2026-01-05
- Cushman & Wakefield Releases 2026 Data Center Development Cost Guide — Cushman & Wakefield, 2026-09-03
- Data center construction costs jump 21% since 2024 — CRE Daily, 2026-08-27
- AI data center rush raises alarm over construction supply chain — Turner & Townsend, 2025-11-05
- Data center construction cost: 2026 benchmarks — Data Center Scouts, 2026-09-28
- Second Quarter 2026 Earnings Call deck — Core Scientific, 2026-07-28
- OpenAI building Stargate with NVIDIA and Oracle — Data Center Dynamics, 2025-11-14
- Form 8-K: Horizon data center and Dell GPU order — IREN, 2025-11-03
- AI data centers: the powered shell providers — Rittenhouse Research, 2026-09-02
- Crusoe tax abatement agreement — Haskell County, Texas, 2026-07-21
- The retrofit premium: converting data centers — Measured AI, 2026-04-13
- How much does an NVIDIA NVL72 cost? — Wing VC, 2026-08
- PUCT sets financial commitments for data center interconnection; Governor pauses permits — White & Case, 2026-09-25
- Texas lawmakers question billions in tax breaks for data centers — Texas Public Radio, 2026-07-28
- Wholesale electricity prices forecast for 2025 — EIA, 2025-01-27
- Data center cost guide — Metro Colo Advisory (EIA data), 2026-10-09
- The marathon: can behind-the-meter data center power solutions endure the decade in the US? — Rabobank, 2026-06-24
- Batch Zero Update — ERCOT, 2026-09-11
- Data center construction costs 2026 — RSMeans by Gordian, 2026-06-25
- Construction Cost Index Q1 2026 — Mortenson, 2026
- Cahill represents initial purchasers in Core Scientific's $3.3 billion notes offering — Cahill Gordon & Reindel, 2026-05-06
- OpenAI Stargate: where the US sites stand — Epoch AI, 2026-04-23
- North America Data Center Trends H2 2025 — CBRE, 2026-02-25
- North America Data Center Trends H1 2026 — CBRE, 2026-08-27
- Hut 8 signs second Beacon Point lease; 704 MW contracted — btw.media, 2026-07-20
- Nvidia anchors Hut 8's $20B AI lease bet in Texas (Financial Times report) — Crypto Briefing, 2026-07-30
Building or financing an AI data center in Texas?
GR1D develops powered-shell and turnkey AI data centers — 20 MW to 150 MW sites with power, fiber and entitlements solved before the first rack arrives. See how we build, browse our sites or talk to us.