Why Small, Bespoke AI Data Centers (20–60 MW) Are Winning the Next Build Cycle
Small data centers — bespoke, single-tenant AI sites of 20 to 60 MW — are winning the 2026–2030 build cycle because they sit below the thresholds that now stall large projects. In Texas a load under 75 MW is not an ERCOT large load: it skips Batch Zero, the $50,000-per-MW security deposit and a study that allocates grid capacity for 2028–2032. Documented sites in this band deliver live halls 7 to 14 months from lease or utility service. This guide also names the limits.
Read as text
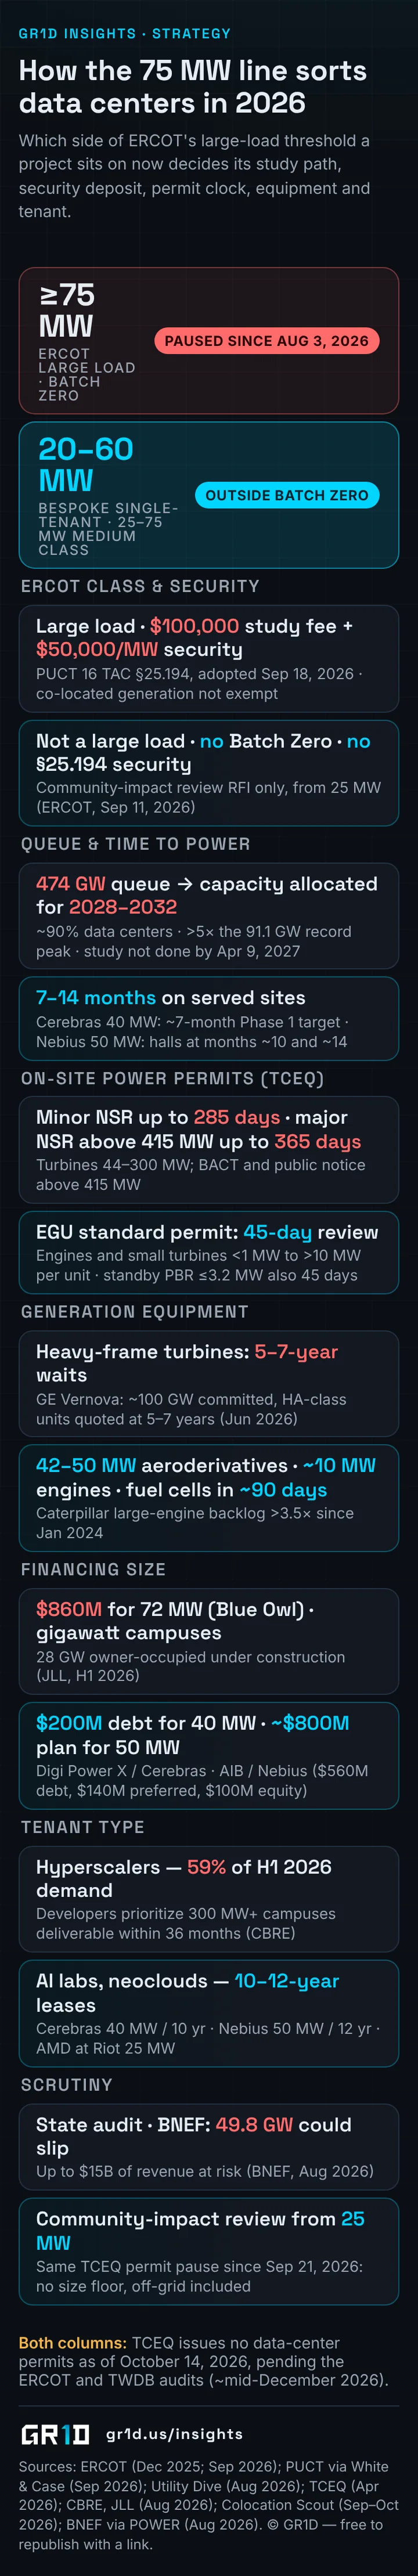
- How the 75 MW line sorts data centers in 2026
- Which side of ERCOT's large-load threshold a project sits on now decides its study path, security deposit, permit clock, equipment and tenant.
- ≥75 MW · ERCOT LARGE LOAD · BATCH ZERO
- ERCOT LARGE LOAD · BATCH ZERO
- PAUSED SINCE AUG 3, 2026
- 20–60 MW · BESPOKE SINGLE-TENANT · 25–75 MW MEDIUM CLASS
- BESPOKE SINGLE-TENANT · 25–75 MW MEDIUM CLASS
- OUTSIDE BATCH ZERO
- ERCOT CLASS & SECURITY
- Large load · $100,000 study fee + $50,000/MW security · PUCT 16 TAC §25.194, adopted Sep 18, 2026 · co-located generation not exempt
- Not a large load · no Batch Zero · no §25.194 security · Community-impact review RFI only, from 25 MW (ERCOT, Sep 11, 2026)
- QUEUE & TIME TO POWER
- 474 GW queue → capacity allocated for 2028–2032 · ~90% data centers · >5× the 91.1 GW record peak · study not done by Apr 9, 2027
- 7–14 months on served sites · Cerebras 40 MW: ~7-month Phase 1 target · Nebius 50 MW: halls at months ~10 and ~14
- ON-SITE POWER PERMITS (TCEQ)
- Minor NSR up to 285 days · major NSR above 415 MW up to 365 days · Turbines 44–300 MW; BACT and public notice above 415 MW
- EGU standard permit: 45-day review · Engines and small turbines <1 MW to >10 MW per unit · standby PBR ≤3.2 MW also 45 days
- GENERATION EQUIPMENT
- Heavy-frame turbines: 5–7-year waits · GE Vernova: ~100 GW committed, HA-class units quoted at 5–7 years (Jun 2026)
- 42–50 MW aeroderivatives · ~10 MW engines · fuel cells in ~90 days · Caterpillar large-engine backlog >3.5× since Jan 2024
- FINANCING SIZE
- $860M for 72 MW (Blue Owl) · gigawatt campuses · 28 GW owner-occupied under construction (JLL, H1 2026)
- $200M debt for 40 MW · ~$800M plan for 50 MW · Digi Power X / Cerebras · AIB / Nebius ($560M debt, $140M preferred, $100M equity)
- TENANT TYPE
- Hyperscalers — 59% of H1 2026 demand · Developers prioritize 300 MW+ campuses deliverable within 36 months (CBRE)
- AI labs, neoclouds — 10–12-year leases · Cerebras 40 MW / 10 yr · Nebius 50 MW / 12 yr · AMD at Riot 25 MW
- SCRUTINY
- State audit · BNEF: 49.8 GW could slip · Up to $15B of revenue at risk (BNEF, Aug 2026)
- Community-impact review from 25 MW · Same TCEQ permit pause since Sep 21, 2026: no size floor, off-grid included
- Both columns: TCEQ issues no data-center permits as of October 14, 2026, pending the ERCOT and TWDB audits (~mid-December 2026).
- Both columns:
What counts as a small data center in 2026?
The phrase has no regulatory definition, and a search for "small modular data center" mostly returns small modular reactors, which are nuclear power plants, not buildings. This article means a bespoke, single-tenant AI facility of 20 to 60 MW, built to suit one operator as a powered shell or turnkey, and sized to stay under the thresholds that now govern large loads.
Three sources draw the band. ERCOT and the Texas PUC treat 75 MW per site as the line between a "large load" and everything else, and the state's audit calls 25–75 MW projects medium facilities (ERCOT, Dec 2025; Utility Dive, Aug 21, 2026). CBRE sees "another potentially important workload band developing around 25 to 75 MW" alongside 2–20 MW infill (CBRE, Aug 2026; Data Center Frontier, Aug 28, 2026). JLL reports enterprise users at 500 kW to 3 MW "struggling to secure capacity" at 1% vacancy (JLL, Aug 2026). The 20–60 MW site sits between them, 15 MW under the line. The twelve phases in How a Data Center Is Built apply unchanged; what changes is which gates it can skip.
What is the 75 MW line in ERCOT, and why does it decide the build?
In ERCOT, a "Large Load" is 75 MW or more at a single site, and the new large-load interconnection process (PGRR 115) does not apply below it (ERCOT, Dec 2025). Batch Zero, the one-time batch study for large loads, covers only that class; loads of 25 to 75 MW are outside it and receive only a Community Impact Review request for information (ERCOT, Sep 11, 2026; Baker Botts, Aug 2026). The PUCT's final rule, 16 TAC §25.194, adopted September 18, 2026, attaches money to the line: a $100,000 study fee and $50,000 per MW of security at 75 MW and above, with no exemption for co-located generation (White & Case, Sep 2026). A 60 MW project is outside the rule and outside the energization pause described below.
What does a 474 GW queue mean for a 2027 energization?
ERCOT's large-load queue reached about 474 GW in August 2026, roughly 90% of it data centers and more than five times the system's record peak (Utility Dive, Aug 5, 2026); that peak is 91.1 GW, set on July 22, 2026 (EIA, Aug 2026). Batch Zero's provisional classification in September put 204 projects (66.4 GW) in the base-load group and 158 projects (about 125–128 GW) in the studied group, and excluded 373 projects totalling 302 GW (ERCOT, Sep 11, 2026). It allocates transmission capacity for 2028 through 2032; Batch 1 opens in summer 2027 (Foley, Mar 2026).
The state audit counts about 300 proposed data centers of 75 MW or more, against 157 medium facilities of 25–75 MW totalling about 8,800 MW (Utility Dive, Aug 21, 2026). BNEF estimates 49.8 GW of Texas load could slip, with up to $15 billion of revenue at risk (POWER, Aug 2026), and puts US development at 5.3 years for hyperscalers and 8.4 years for everyone else (BNEF, Jul 2026). A 2027 energization is not on offer to a grid-served Texas load of 75 MW or more; a 20–60 MW load on a served site can still get one.
How fast can a 20–60 MW AI data center be built?

Read as text
- Months, not years: AI sites versus the Batch Zero window
- Months from lease signature, utility service or site purchase to live halls, as each source reports. Shaded band: when Batch Zero allocates ERCOT grid capacity to loads of 75 MW or more.
- Digi Power X / Cerebras · Columbiana, AL · 40 MW · signed May 4, 2026
- Columbiana, AL · 40 MW · signed May 4, 2026
- ~7 mo target · Phase 1 Dec 2026 · Phase 2 Mar 2027
- Phase 1 Dec 2026 · Phase 2 Mar 2027
- Nscale / Ionic · Ward County, TX · 234 MW · empty shell Jan 2026
- Ward County, TX · 234 MW · empty shell Jan 2026
- ~9 mo · Go-live Oct 1, 2026 · rent from Aug
- Go-live Oct 1, 2026 · rent from Aug
- IREN Horizon 1 · Texas · 50 MW IT · 200 kW racks · Microsoft contract Nov 2025
- Texas · 50 MW IT · 200 kW racks · Microsoft contract Nov 2025
- ~9 mo · Accepted Aug 13, 2026
- Accepted Aug 13, 2026
- AIB / Nebius CLT1 · South Carolina · 50 MW IT · utility service Oct 1, 2026
- South Carolina · 50 MW IT · utility service Oct 1, 2026
- ~10 / ~14 mo · Hall 1 · Hall 2 targets
- Hall 1 · Hall 2 targets
- Hut 8 Vega · Texas · 205 MW · 180 kW racks · site bought Jul 2024
- Texas · 205 MW · 180 kW racks · site bought Jul 2024
- <12 mo · Energized Jun 2025
- Energized Jun 2025
- DC BLOX Huntsville · Alabama · 20 MW · 2018 reference, pre-AI
- Alabama · 20 MW · 2018 reference, pre-AI
- 22 weeks · Brasfield & Gorrie
- Brasfield & Gorrie
- 0 · 6 · 12 · 18 · 24 months · Jan 2028 → 2032: Batch Zero allocations
- 12
- 18
- 24 months
- Jan 2028 → 2032: Batch Zero allocations
- Delivered · Target / scheduled · Second phase · 2018 reference · Batch Zero window (≥75 MW grid loads, from today)
- Delivered
- Target / scheduled
- Second phase
- 2018 reference
- Batch Zero window (≥75 MW grid loads, from today)
- CBRE'S CAVEAT (JAN 2026) · 12–18 mo · Sub-50 MW build claims "no longer reflect the market"; interconnection runs 24–48+ months wherever utility upgrades are needed.
- BATCH ZERO STUDY · Apr 9, 2027 · "We will not have the study done by April 9, 2027" (ERCOT, Sep 11, 2026). Batch 1 opens summer 2027.
- OUTSIDE THE BATCH · 157 sites · Medium facilities (25–75 MW) ≈ 8.8 GW, versus ~300 proposed at ≥75 MW (Utility Dive, Aug 2026).
| Project | Size | Documented timeline | Source |
|---|---|---|---|
| Digi Power X / Cerebras, AL | 40 MW | Signed May 4, 2026 → Phase 1 Dec 2026 (~7 mo target); Phase 2 Mar 2027 | Colocation Scout, Oct 2026 |
| AIB / Nebius, SC | 50 MW IT | Utility service Oct 1, 2026 → halls at months ~10 and ~14 (targets) | AIB 8-K via Colocation Scout, Sep 2026 |
| IREN Horizon 1, TX | 50 MW IT, 200 kW/rack | Microsoft contract Nov 2025 → accepted Aug 13, 2026 (~9 mo); originally targeted for Q4 2025 | IREN 8-K, Aug 2026; IREN, May 2025 |
| Nscale / Ionic, Ward County, TX | 234 MW lease | Empty shell ~Jan 2026 → go-live Oct 1, 2026 in the July prospectus (~9 mo); cash rent on 234 MW of operating capacity from August 2026, on a campus energized since 2023 | Ionic 424B4 via Colocation Scout, Jul 2026; Ionic Digital, Aug 2026 |
| Hut 8 Vega, TX | 205 MW, 180 kW/rack | Site bought Jul 2024 → energized Jun 2025 (<12 mo) | Hut 8, Jun 2025 |
| DC BLOX Huntsville, AL | 20 MW | 22 weeks (2018, pre-AI) | Brasfield & Gorrie, 2018 |
The sub-75 MW cases — 40, 50 and 50 MW — run 7 to 14 months, and two of the three are still targets. The two fastest large sites were brownfield power plays: Nscale took over an empty shell on a campus energized since 2023; Hut 8 bought Vega in July 2024 and energized 205 MW eleven months later. Applied Digital's 100 MW Polaris Forge 1 also delivered its 2025 phases on schedule (Applied Digital, Nov 2025). Every fast case had existing power or a sub-75 MW block; the lesson is as much "buy power first" as "build small."
CBRE's caveat: "traditional 12–18 month timelines for sub-50 MW facilities no longer reflect the market," and interconnection runs 24 to 48 months or more wherever utility upgrades are needed (Data Center Frontier on CBRE, Jan 2026). A small building on a site that needs a new substation is not fast; see Realistic Data Center Timelines in 2026.
Can a small data center bring its own power in Texas?
In normal times, yes, and the permit calendar favors this scale: TCEQ's air permit tiers scale with generating capacity, not the data center's load (TCEQ Air Permits Division, Apr 2026):
| On-site generation | TCEQ pathway | Review time |
|---|---|---|
| Standby engines ≤3.2 MW, ≤876 hours per year | Permit by rule §106.511 | 45 days |
| Engines and small turbines, <1 MW to >10 MW per unit | Electric generating unit (EGU) standard permit | 45 days |
| Turbines 44–300 MW | Minor New Source Review | Up to 285 days |
| Plants above 415 MW | Major New Source Review (BACT, public notice) | Up to 365 days |
The equipment sorts the same way. GE Vernova has about 100 GW of heavy-frame turbines committed and quotes five-to-seven-year waits for HA-class units (Manufacturing Magazine, Jun 2026). What fits a 20–60 MW block is smaller: aeroderivative turbines at 42–50 MW per unit (Data Center Frontier, Feb 2026), reciprocating engines such as Wärtsilä's 34SG at about 10 MW each (Power Engineering, Apr 2026) and fuel cells, where Bloom claims site power in 90 days (Power Engineering, Jul 2025). None of it is on the shelf: Caterpillar's large-engine backlog has grown more than 3.5 times since January 2024 (Manufacturing Dive, May 2026), and on-site gas costs more than $120 per MWh (Ascend Analytics, May 2026). The options are compared in How Data Centers Are Powered.
Who is leasing 20–60 MW single-tenant data centers?
Inference tenants. McKinsey projects AI inference load rising from 20.9 GW in 2025 to 93.3 GW in 2030, overtaking training (McKinsey, Feb 2026). Training tolerates about 100 milliseconds between regions and stays in remote gigawatt campuses (DCD, Mar 2026); inference serves users, which makes the 20–60 MW site an inference play. JLL puts hyperscalers at 59% of H1 2026 demand, neoclouds at 11% and pure-play AI companies at 7% (JLL, Aug 2026); the last two are the natural single-tenant customers, and in Dallas–Fort Worth "demand is growing for sites below 75 MW" (Data Center Frontier, Aug 28, 2026). The 2026 leases: Cerebras took 40 MW at Digi Power X for 10 years and Nebius 50 MW at AIB for 12 (Colocation Scout, Oct 2026), and AMD took 25 MW at Riot Platforms' Rockdale, Texas site (Riot Platforms Form 8-K, Jan 16, 2026).
How many GPUs fit in a 20 MW data center?

Read as text
- How many GPUs fit in 20 MW? About 11,900 today
- Derived from rack power and GPUs per rack; facility overhead, network and storage racks excluded. One tile is one rack.
- TODAY · NVIDIA GB200 NVL72 (SEMIANALYSIS) · 20 MW · IT load · ÷ · 120 kW · per rack (123.6 kW with losses) · = · ≈165 racks · liquid-cooled above ~40 kW · × · 72 GPUs · per rack · = · ≈11,900 GPUs · derived · 165 racks. Operators already run denser: Hut 8 Vega 180 kW, IREN Horizon 1 200 kW per rack.
- H2 2027 · NVIDIA KYBER, RUBIN ULTRA NVL576 (GTC VIA TECHRADAR) · 20 MW · IT load · ÷ · 600 kW · per rack · = · ≈33 racks · same 20 MW · × · 576 dies · per rack · = · ≈19,000 GPU dies · derived · 33 racks. Same tile scale as above: five times the rack power, one fifth of the rack count.
- WHERE MOST OF THE INDUSTRY STILL IS · <10 kW · Modal rack for 69% of operators (Uptime Institute, 2026). Liquid cooling becomes necessary above roughly 40 kW per rack; the AI racks above run 3–15× that.
- WHAT FILLS THEM: AI INFERENCE LOAD (MCKINSEY, FEB 2026) · 2025 · 20.9 GW · 2030 · 93.3 GW · Inference overtakes training by 2030; inference serves users, which is the workload a 20–60 MW site is built for.
About 12,000 current-generation GPUs, by our arithmetic. An NVIDIA GB200 NVL72 rack holds 72 GPUs and draws about 120 kW (123.6 kW with conversion losses); anything above roughly 40 kW per rack needs liquid cooling (SemiAnalysis, Jul 2024). Twenty megawatts of IT load divided by 120 kW is about 165 racks; 165 racks times 72 GPUs is about 11,900 GPUs. That is a derived figure — IT load, not facility load, no network or storage racks — but the order of magnitude holds; Hut 8 and IREN already design at 180 and 200 kW per rack.
NVIDIA's Kyber rack for Rubin Ultra NVL576 is specified at 600 kW for the second half of 2027 (TechRadar, Mar 2025); at that density the same 20 MW is about 33 racks and roughly 19,000 GPU dies. For context, 69% of operators still report a modal rack under 10 kW (Uptime Institute, Aug 2026). The useful metric is GPUs per megawatt, not square footage.
What does a 20–60 MW site cost to build and finance?
The 2026 comps run from about $5 million to $16 million per MW, and the spread says more about scope than size. Digi Power X has a $200 million Goldman-syndicated debt commitment for its 40 MW Cerebras site (Colocation Scout, Oct 2026). AIB's plan for 50 MW is about $800 million — $560 million of debt, $140 million of preferred and $100 million of equity, about $16 million per MW (derived) (AIB 8-K via Colocation Scout, Sep 2026). Blue Owl paid $860 million for 72 MW, about $11.9 million per MW (CBRE, Aug 2026). Reported build costs are lower: $6–7 million per MW at IREN's 50 MW Horizon 1 (IREN, May 2025) and $7–10 million per MW at TeraWulf's 600 MW (Latitude Media, 2026), so the data show no clean size discount, and small-site operating cost per MW is not well documented. The debt is available at a price: JLL expects more than $700 billion of permanent debt over 30 months and prices non-credit tenants 200–300 basis points wider (JLL, Aug 2026).
Where does the small-site thesis break down?
- The TCEQ pause has no size floor. Since September 21, 2026 TCEQ issues no permits sought by data center projects, behind-the-meter ones included, until the audits finish around mid-December (Bracewell, Sep 2026). Being under 75 MW helps with ERCOT and does nothing for an air permit this quarter.
- Scrutiny starts at 25 MW, not 75. Community-impact review requests apply from 25 MW (Utility Dive, Aug 21, 2026), and BNEF calls local opposition a "material constraint" (BNEF, Jul 2026).
- The biggest buyers want gigawatts. Hyperscalers are 59% of demand with 28 GW of owner-occupied capacity under construction (JLL, Aug 2026), and developers prioritize campuses of 300 MW or more within 36 months (CBRE, Aug 2026).
- Tenant credit is the cost. The 200–300 bps premium is real, and Latitude Media counts more than 100 neoclouds, most "very early-stage or GPU resellers" (Latitude Media, 2026).
- Not every Texas market is tight. Houston's vacancy was 19.7% in H1 2025 (CBRE, Sep 2025) against 2.3% in Austin–San Antonio, where 462 MW under construction was 97% preleased (CBRE, Sep 2025). In Houston a 20 MW site competes on price and live power.
Frequently asked questions
What is a "large load" in ERCOT?
A load of 75 MW or more at a single site. Large loads go through Batch Zero, pay a $100,000 study fee and post $50,000 per MW of security; loads of 25–75 MW are outside Batch Zero and get a community-impact review request instead.
How many MW is a small data center?
There is no official definition. The practical 2026 band for a bespoke single-tenant AI site is 20–60 MW: above the 2–20 MW infill and 500 kW–3 MW enterprise deals CBRE and JLL describe, below ERCOT's 75 MW large-load line.
How fast can a 20–60 MW AI data center energize?
Documented cases run 7 to 14 months from lease or utility service on sites with power in hand: Cerebras' 40 MW targets about seven months to Phase 1, and Nebius' 50 MW halls land at months 10 and 14.
Can a small data center run behind the meter in Texas?
In normal times, yes: engines and small turbines up to and above 10 MW per unit qualify for TCEQ's EGU standard permit with a 45-day review, against up to 365 days for plants above 415 MW. Since September 21, 2026, however, TCEQ has paused all data-center permits, off-grid projects included.
How many GPUs fit in 20 MW?
About 11,900 Blackwell-class GPUs, by our arithmetic: 20 MW of IT load divided by 120 kW per GB200 NVL72 rack is roughly 165 racks of 72 GPUs. At the 600 kW Kyber rack planned for 2027, the same 20 MW holds about 33 racks and 19,000 GPU dies.
Sources
- Large Load Interconnection Process Q&A — ERCOT, 2025-12-24
- Batch Zero Update — ERCOT, 2026-09-11
- Texas hits pause on data center interconnections — Utility Dive, 2026-08-05
- Texas PUC approves data center audit — Utility Dive, 2026-08-21
- Texas Large Load Interconnection Update: ERCOT Batch Zero Pause and Verification Process — Baker Botts, 2026-08-17
- PUCT sets financial commitments for data center interconnection; Governor pauses permits — White & Case, 2026-09-25
- ERCOT's proposed Batch Zero process: what developers of large loads need to know — Foley & Lardner, 2026-03-19
- Texas audit could delay 49.8 GW of data center load, BNEF warns — POWER, 2026-08-06
- Governor Abbott orders TCEQ to pause all permit issuance for data center projects — Bracewell, 2026-09-23
- Air permitting for data centers (AAPCA presentation) — TCEQ Air Permits Division, 2026-04-07
- Six things to know about BNEF's new US data center capacity outlook — BloombergNEF, 2026-07-29
- Hut 8 energizes Vega data center — Hut 8 via Globe Newswire, 2025-06-30
- Nscale Ward County goes live: Ionic lease terms — Colocation Scout (Ionic Form 424B4), 2026-07-28
- Digi Power X secures $200M debt commitment for Columbiana 40 MW — Colocation Scout, 2026-10-13
- AIB signs Nebius for 50 MW at CLT1 — Colocation Scout (AIB Form 8-K), 2026-09-30
- Data center deals tracker — Colocation Scout, 2026-10-13
- Applied Digital completes Phase II ready-for-service at Polaris Forge 1 — Applied Digital, 2025-11-24
- IREN reports Q3 FY25 results — IREN, 2025-05-14
- DC BLOX Huntsville: 20 MW in 22 weeks — Brasfield & Gorrie, 2018
- CBRE's 2026 data center outlook: demand surges as delivery becomes the constraint — Data Center Frontier, 2026-01-22
- CBRE: record data center construction fails to ease capacity crunch — Data Center Frontier, 2026-08-28
- North America Data Center Trends H1 2026 — CBRE, 2026-08-27
- Data center demand exceeds expectations in H1 2026 — JLL, 2026-08-11
- North America Data Center Trends H1 2025: Houston — CBRE, 2025-09-08
- North America Data Center Trends H1 2025: Austin–San Antonio — CBRE, 2025-09-08
- Uptime Institute Global Data Center Survey 2026: Data Center Growth — Uptime Institute, 2026-08
- The future of AI workloads — McKinsey, 2026-02-24
- Training built the campuses; inference will choose the markets — Data Center Dynamics (sponsored), 2026-03-17
- How AI neoclouds are reshaping the grid — Latitude Media, 2026
- GE Vernova gas turbine backlog stretches to 2030 as data centers outbid utilities — Manufacturing Magazine, 2026-06-06
- Caterpillar to triple power generation capacity, raises 2030 targets — Manufacturing Dive, 2026-05-01
- Aeroderivative turbines move to the center of AI data center power strategy — Data Center Frontier, 2026-02-25
- Wärtsilä 34SG engines for data center power — Power Engineering, 2026-04-16
- Oracle, Bloom Energy strike data center power deal — Power Engineering, 2025-07-25
- Large load interconnection queues and data center grid access — Ascend Analytics, 2026-05-05
- GB200 hardware architecture and component supply chain — SemiAnalysis, 2024-07-17
- Megawatt-class AI server racks may become the norm before 2030 as NVIDIA displays 600 kW Kyber rack design — TechRadar, 2025-03-29
- Hourly peak load in ERCOT set a new record, exceeding 91 GW on July 22 — U.S. Energy Information Administration, 2026-08-03
- Form 8-K, January 16, 2026 (AMD lease at Rockdale) — Riot Platforms via SEC, 2026-01-16
- IREN Form 8-K exhibit 99.1: Horizon 1 accepted by Microsoft — IREN via SEC, 2026-08-13
- Ionic Digital Announces Second Quarter 2026 Results — Ionic Digital via GlobeNewswire, 2026-08-19
Building or financing an AI data center in Texas?
GR1D develops powered-shell and turnkey AI data centers — 20 MW to 150 MW sites with power, fiber and entitlements solved before the first rack arrives. See how we build, browse our sites or talk to us.