AI Data Center Site Selection: The Power, Fiber, Water, Land and Permitting Checklist (Texas Edition)
Data center site selection criteria in 2026 reduce to one ranked question, how fast a parcel can get power, followed by fiber, water, land, zoning, permits, incentives and community risk. In Texas the test is sharper: a 75 MW line that decides whether a project enters ERCOT's Batch Zero, three state orders since August 3, counties that cannot zone, and a sales-tax exemption facing repeal in January. This is the checklist we run, with weights, data sources and pass/fail gates.
Read as text
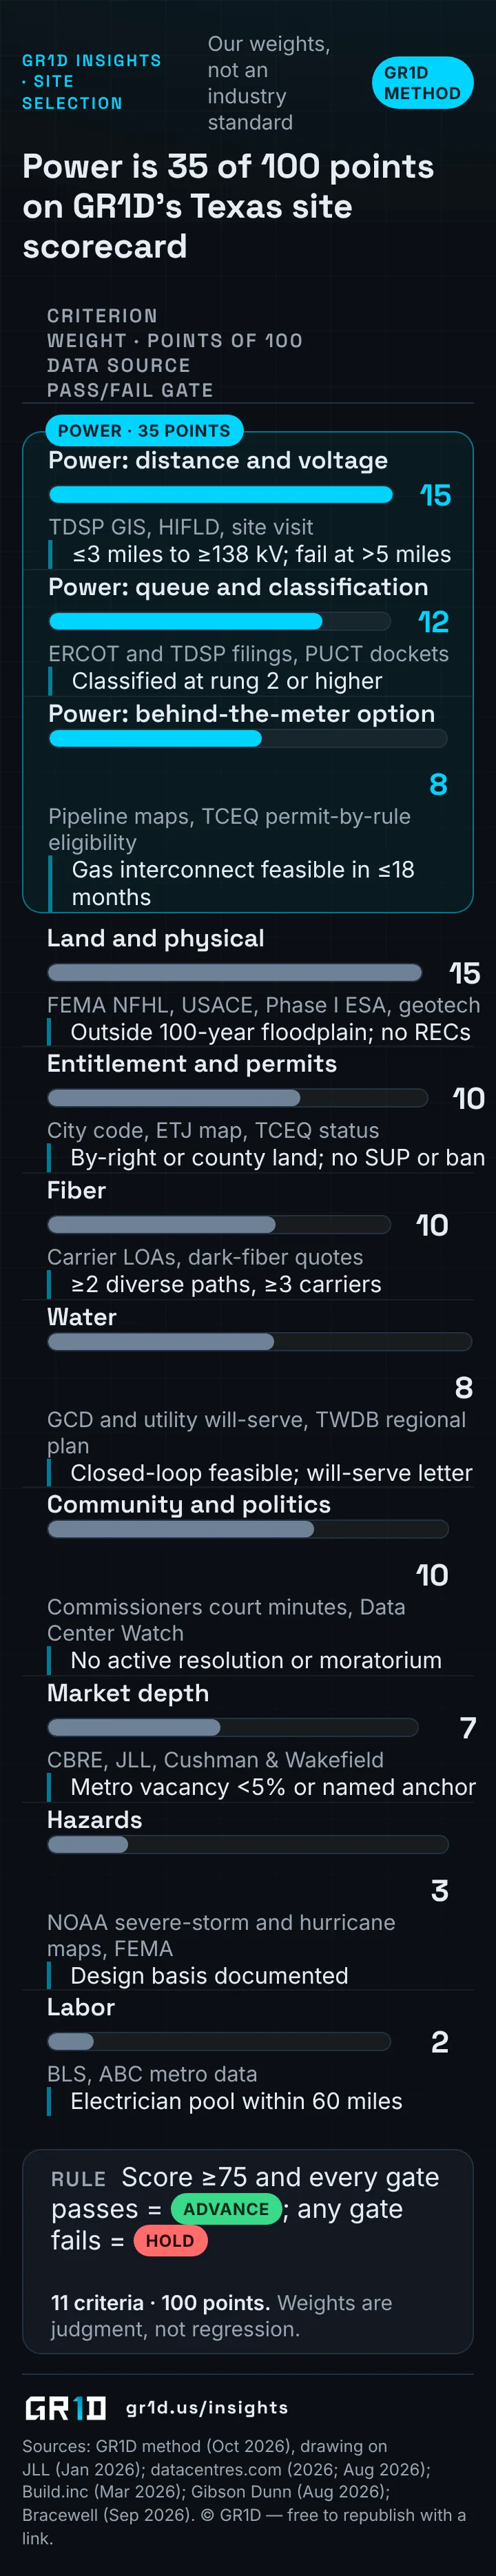
- Power is 35 of 100 points on GR1D's Texas site scorecard
- GR1D INSIGHTS · SITE SELECTION
- Our weights, not an industry standard · GR1D METHOD
- Our weights, not an industry standard
- GR1D METHOD
- CRITERION
- WEIGHT · POINTS OF 100
- DATA SOURCE
- PASS/FAIL GATE
- POWER · 35 POINTS
- Power: distance and voltage
- 15
- TDSP GIS, HIFLD, site visit
- ≤3 miles to ≥138 kV; fail at >5 miles
- Power: queue and classification
- 12
- ERCOT and TDSP filings, PUCT dockets
- Classified at rung 2 or higher
- Power: behind-the-meter option
- Pipeline maps, TCEQ permit-by-rule eligibility
- Gas interconnect feasible in ≤18 months
- Land and physical
- FEMA NFHL, USACE, Phase I ESA, geotech
- Outside 100-year floodplain; no RECs
- Entitlement and permits
- 10
- City code, ETJ map, TCEQ status
- By-right or county land; no SUP or ban
- Fiber
- Carrier LOAs, dark-fiber quotes
- ≥2 diverse paths, ≥3 carriers
- Water
- GCD and utility will-serve, TWDB regional plan
- Closed-loop feasible; will-serve letter
- Community and politics
- Commissioners court minutes, Data Center Watch
- No active resolution or moratorium
- Market depth
- CBRE, JLL, Cushman & Wakefield
- Metro vacancy <5% or named anchor
- Hazards
- NOAA severe-storm and hurricane maps, FEMA
- Design basis documented
- Labor
- BLS, ABC metro data
- Electrician pool within 60 miles
- RULEScore ≥75 and every gate passes = ADVANCE; any gate fails = HOLD
- RULE
- ADVANCE
- HOLD
- 11 criteria · 100 points. Weights are judgment, not regression.
- 11 criteria · 100 points.
Why does speed to power outrank every other site criterion?
JLL's 2026 outlook calls "speed to power" the primary site-selection criterion for 2027 deliveries; location and cost "take a back seat" (JLL via Data Center Frontier, Jan 2026). Cushman & Wakefield measures new large-load power delivery at about 4.4 years globally and 5 years in the Americas, while buyers want capacity in 18 to 24 months (Propmodo, May 2026). A parcel that cannot close that gap is not a data center site at any price.
A utility indicating a 2030 connection "is not a bankable asset" when grid delays in major hubs exceed four years (Datacentre Magazine, Jan 2026), and "the most valuable data center asset is not land — it's land with power or grid interconnect already attached" (Foley, Aug 2026). The checklist below runs in the order of GR1D's weights, power first; what happens after site selection is in How a Data Center Is Built.
What is the 2026 Texas rulebook: 75 MW, Batch Zero, SB 6 and three state orders?
Senate Bill 6, signed in June 2025, made 75 MW the line: loads at or above it enter ERCOT's large-load process through their utility, disclose on-site backup and accept emergency curtailment (Troutman, Aug 2026). Batch Zero, ERCOT's batch study of loads of 75 MW or more, was approved June 18, 2026; results are due April 9, 2027, a date ERCOT says it will miss (Global Data Center Hub, Aug 2026; ERCOT, Sep 11, 2026). PUCT rule 16 TAC §25.194, adopted September 18 and effective October 8, prices entry at a $100,000 study fee plus $50,000 per MW of security (White & Case, Sep 2026).
The queue held about 474 GW in August 2026, roughly 90% data centers and more than five times ERCOT's record peak of 91.1 GW, set July 22, 2026 (Gibson Dunn, Aug 2026; EIA, Aug 2026). Loads of 25 to 75 MW sit outside Batch Zero but received audit information requests covering about 8,766 MW (Gibson Dunn). Gate by gate: Getting Power in Texas.
Power: how do you prove a site's time to power?
Each of the four power tests needs a document, not a conversation.
Distance and voltage. One to three miles from a substation of 138 kV or higher; beyond five miles a site usually needs a dedicated line (datacentres.com guide, 2026). Prefer 345, 230 and 138 kV corridors (Build.inc, Mar 2026).
Utility and queue. Oncor serves DFW and the northeast Austin suburbs, LCRA the territory south of Austin and Austin Energy the city (CBRE, Sep 2025); CenterPoint serves Houston, where about 14 GW of requests were expected to qualify for Batch Zero (Utility Dive, Jul 2026). Oncor holds more than 38,000 MW of large-load requests, quotes transformers near 36 months and tells unqueued DFW sites to expect 2028–29 energization (datacentres.com, Aug 2026).
Classification. Below 75 MW the project stays in the utility's own process; at 75 MW and above it is a Batch Zero large load with the fee, the security and, today, the pause. Ask for the classification letter, not the queue number.
Behind-the-meter feasibility. On-site gas is "openly accepted" by the market (Data Center Knowledge, Sep 2026) and adds roughly $1.5–2.0M per MW (datacentres.com guide), but the September 21 order reaches BTM projects: New Source Review permits are paused and permits by rule are "less clear" (Bracewell, Sep 2026). A BTM plan without an issued air permit is a plan, not a path; see How Data Centers Are Powered.
We rank the evidence on a four-rung ladder: power nearby; studied (utility load study on file, ERCOT 25/75 MW classification determined); delivery path (facilities study, transformer slot, security posted at the $50,000 per MW default) (Global Data Center Hub); and contractually credible (an executed interconnection or supply agreement with a date, or BTM gas with a pipeline interconnect and an issued air permit). Pricing follows the ladder: pre-entitled, power-reserved sites carry a 15–20% premium (datacentres.com, Aug 2026).

Read as text
- Time to power is proved with documents, rung by rung
- What counts as evidence at each rung, and what it says about the power date. Advance a site only once it reaches rung 2.
- RUNG · 1
- RUNG
- Power nearby
- PROXIMITY ONLY
- EVIDENCE
- Substation of ≥138 kV within 1–3 miles (345, 230, 138 kV corridors preferred)
- Beyond 5 miles: usually a dedicated line
- TDSP GIS, HIFLD map, site visit
- On its own: a red flag. Power "nearby" with no utility study is on our kill-or-discount list.
- On its own:
- RUNG · 2
- Studied
- MINIMUM TO ADVANCE
- Utility (TDSP) load study on file
- ERCOT 25/75 MW class determined: a letter, not a queue number
- 75 MW or more: $100,000 study fee
- Sets the path: under 75 MW stays in the utility's process; 75 MW+ enters Batch Zero, paused since Aug 3, 2026.
- Sets the path:
- RUNG · 3
- Delivery path
- SLOT AND SECURITY
- Facilities study
- Transformer slot · Oncor quotes ~36 months
- Security posted: $50,000/MW default
- Time to power: Oncor tells unqueued DFW sites to expect energization in 2028–29.
- Time to power:
- RUNG · 4
- Contractually credible
- SIGNED, WITH A DATE
- Executed interconnection or supply agreement with an energization date
- or behind-the-meter gas: pipeline interconnect plus an issued air permit (adds ~$1.5–2.0M per MW)
- Caveat: TCEQ has issued no data-center permits since Sep 21, 2026, BTM included. Without an issued air permit, BTM is a plan, not a path.
- Caveat:
- TIME TO NEW LARGE-LOAD POWER (C&W, MAY 2026) · Buyers want · 18–24 mo · Global delivery · ~4.4 yrs · Americas delivery · ~5 yrs · 0 · 1 · 2 · 3 · 4 · 5 yrs
- A UTILITY'S 2030 PROMISE · Not bankable · "Is not a bankable asset" when grid delays in major hubs exceed four years (JLL, Jan 2026).
- PRICING FOLLOWS THE LADDER · +15–20% · Pre-entitled, power-reserved DFW sites over raw land at $150,000–400,000 per acre (datacentres.com, Aug 2026).
Fiber: two diverse paths or no deal
Two physically diverse paths is the minimum (Build.inc). New builds take 6 to 18 months, and primary markets offer 30 to 80-plus carriers against fewer than 10 in secondary ones (datacentres.com guide). Two Texas corridors are under construction, South Dallas (Wilmer, Red Oak, Lancaster, Midlothian) and Austin–Bastrop, both homing to the Dallas and Fort Worth carrier hubs on an 800G statewide backbone (Data Center Knowledge, Feb 2026). Evidence: carrier letters of availability, dark-fiber IRU quotes and a meet-me-room plan.
Water: what will TWDB, drought and closed-loop rules require?
Texas data centers use about 25 billion gallons a year; HARC projects 29 to 161 billion by 2030, up to 2.7% of state use (HARC, Jan 2026). UT Austin puts the 2040 share above 9%, the draft 2027 State Water Plan does not mention data centers against a $174 billion 50-year need, and 65% of Texas was in drought in May 2026 (E&E News, May 2026). The governor wants closed-loop systems mandated (Click2Houston, Jun 2026), TWDB now compels water-use reporting (DLA Piper) and Kerrville requires water-capacity approval and cooling-type disclosure (KBTX, Jun 2026). Tests: the source, water rights or a will-serve letter, groundwater district rules, the TWDB regional plan, a drought contingency plan, closed-loop by default.
Land: how many acres per MW, and what kills a parcel?
AI campuses run 100 to 500-plus acres (Build.inc). Observed Texas density varies almost fourfold, from about 0.9 acres per MW at Vantage's roughly 1 GW, 900-acre Denton County campus to about 0.25 at the Poolside/CoreWeave 2 GW, 500-acre West Texas project (ratios computed), and DFW land runs $150,000–400,000 per acre, with Related Digital's $92 million for 380 acres in Melissa at about $242,000 (datacentres.com, Aug 2026; Center Square via AOL, Oct 2025). Ratios depend on density, cooling and on-site generation; treat them as a sanity check.
Physical gates: outside the FEMA 100-year floodplain, and in Houston the 500-year as well (TRG Datacenters, Apr 2026); a geotechnical report; a wetlands and USACE determination; a Phase I ESA with no recognized environmental conditions; noise setbacks; a county road-use agreement; room to expand.
Zoning in Texas: counties cannot, cities can
Counties have no zoning authority under Dillon's rule; their tools are abatements and road-use agreements (KBTX, Jun 2026; KLTV, Jul 2026), and when they act they cite platting, road and drainage powers under Local Government Code chapters 81 and 232 (Anderson County R-04-2026). Home-rule cities zone under chapter 211: San Marcos banned data centers 4–3 on June 16, 2026 (KBTX/Texas Tribune, Jun 2026) after denying a $1.5 billion, 200-acre project in March (Data Center Frontier, Mar 2026), and Lockhart requires heavy-industrial zoning plus a specific use permit. Nearly half of 248 planned Texas data centers are in unincorporated areas. Test: the city-limit and ETJ map, the zoning district and the permitted-use table. By-right or unzoned county land passes; a special use permit or a ban fails (Reed Smith, Jun 2025).
Permits: six months in normal times, and the September 21 order
The stack is TCEQ New Source Review air, TPDES wastewater, stormwater, platting and building permits, about six months in normal times against 24-plus in some California jurisdictions (datacentres.com guide). Since September 21 TCEQ issues no data-center permits until ERCOT's review ends, and "no state agency shall proceed with regulatory approvals" (Bracewell, Sep 2026; DLA Piper, Sep 2026). TCEQ said on October 14 that applications can be submitted but "will not advance through the review process"; TCEQ's own records, compiled by FracTracker Alliance through October 16, nonetheless show 14 gas plant or generator applications expedited or assigned to engineers and 11 construction stormwater coverages approved (FracTracker, Oct 19, 2026). The site test does not change: an application on file is not a permit, and a TCEQ permit on the critical path before mid-December is a hold.
What Texas data center incentives exist, and will they survive 2027?
The Tax Code §151.359 sales-tax exemption requires a single-occupant facility of 100,000 square feet, $200 million of capital investment within five years and 20 qualifying jobs, and runs 10 years at $200–250 million or 15 years at $250 million or more, with a year-five audit and clawback (Texas Comptroller, Oct 2026). A large-project tier under §151.3595 sets 40 jobs, 250,000 square feet, 20 MW of transmission capacity and $500 million, according to Public Citizen's Senate Finance testimony (Public Citizen, Jul 2026); a 2023 Senate Research Center bill analysis confirms the 250,000-square-foot and $500 million floors (Senate Research Center, May 2023). Around it: JETI, chapter 312 county abatements and 33 chapter 380/381 agreements; the exemption cost $1.1 billion in 2025 and about $3.2 billion this biennium (Public Citizen). On June 10, 2026 the governor recommended repeal in the session that opens January 12, 2027 (Click2Houston, Jun 2026; KXII, Aug 2026). A pro forma that depends on §151.359 beyond 2027 is a red flag, and the scorecard below gives incentives no points.
How much does community opposition cost a schedule?
Data Center Watch counted about $130 billion across 75-plus US projects blocked or delayed in Q1 2026 (Data Center Watch, Q1 2026). The gap is the mechanism: 93% support data centers nationally and 35% locally (JLL via Data Center Frontier, Jan 2026), and Gallup found seven in ten opposed to one nearby (E&E News). In Texas, Hill County rescinded a moratorium after a $100 million lawsuit and Hood County withdrew one after an attorney general opinion was requested (KBTX/Texas Tribune); Angelina and Anderson counties are asking the Legislature for setback, noise and water authority in January 2027 (KLTV, Jul 2026; KXII, Aug 2026). JLL budgets up to 24 months of pre-development engagement (Datacentre Magazine, Jan 2026). Our test: twelve months of commissioners court minutes; an active resolution or moratorium fails the gate.
Where are the best places to build a data center in Texas?
Cushman & Wakefield ranks Dallas–Fort Worth the world's number-one data center market on 24 metrics across 107 markets, Austin–San Antonio the top secondary market and West Texas the top tertiary market with 2.9 GW under construction (Dallas Innovates, Aug 2026; Propmodo, May 2026). Texas has 6.5 GW under construction and JLL expects it to pass Virginia by 2030 (W.Media, Feb 2026). Houston's 19.7% vacancy is the state's only slack (CBRE, Sep 2025), which is why the market gate reads "vacancy under 5% or named anchor".

Read as text
- DFW builds the most; Houston holds Texas's only slack
- The numbers that matter for site selection, by submarket. Texas has 6.5 GW under construction (JLL).
- Dallas–Fort Worth · C&W #1 WORLDWIDE
- Austin–San Antonio · C&W #1 SECONDARY
- Houston · C&W TOP TIER, #3
- West Texas · C&W #1 TERTIARY
- UTILITY AND POWER
- Oncor: >38 GW of large-load requests; transformers ~36 months · Unqueued sites: energization 2028–29
- Oncor (NE suburbs), LCRA (south), Austin Energy (city) · Austin–Bastrop fiber corridor under construction
- CenterPoint: ~14 GW expected to qualify for Batch Zero · Behind-the-meter (BTM) studies, per CBRE
- Gas plus wind · Planned 765 kV backbone · $9.4B, 1,100 miles
- VACANCY · Bar 0–20%; dashed line = GR1D 5% gate
- Bar 0–20%; dashed line = GR1D 5% gate
- <1% · JLL, Aug 2026 · 39.6 of 1,432.8 MW available · (CBRE, H1 2026)
- 2.3% · CBRE, H1 2025
- 19.7% · CBRE, H1 2025 · Fails the 5% gate without a named anchor
- n/a · No vacancy series
- UNDER CONSTRUCTION · Bar 0–3,202 MW
- Bar 0–3,202 MW
- 3,202 MW · JLL, Aug 2026
- 462 MW · CBRE, H1 2025 · 97% preleased
- 15 MW · CBRE, H1 2025 · Due by year-end 2026
- 2.9 GW · C&W, May 2026
- LAND, $ PER ACRE
- $150,000–400,000 · Related Digital: $92M for 380 acres in Melissa, ~$242,000/acre
- Not sourced
- NOTABLE
- Vantage ~1 GW on 900 acres · QTS 180 MW · Stack 220 MW
- San Marcos ban, Jun 16, 2026 (4–3) · Hays County resolution
- Physical gate: outside the 100- and 500-year floodplains
- Stargate Abilene: >5 GW plan · Poolside/CoreWeave: 2 GW, 500 acres
- Corpus Christi / South Texas and East Texas: no sourced 2026 market data. Broker vacancy figures are not like-for-like.
- Corpus Christi / South Texas and East Texas: no sourced 2026 market data.
- GR1D market gate: vacancy <5% or a named anchor
| Submarket | Utility and power | Vacancy | Under construction | Land and notable |
|---|---|---|---|---|
| Dallas–Fort Worth | Oncor; >38 GW requested; ~36-month transformers | <1% (JLL); 39.6 MW available of 1,432.8 MW (CBRE H1 2026) | 3,202 MW (JLL); 2,297 MW absorbed H1 2026 | $150,000–400,000 per acre; Vantage ~1 GW Denton Co.; QTS 180 MW; Stack 220 MW |
| Austin–San Antonio | Oncor, LCRA, Austin Energy; Austin–Bastrop fiber | 2.3% (H1 2025) | 462 MW, 97% preleased (H1 2025) | Land not sourced; San Marcos ban; Hays County resolution |
| Houston | CenterPoint; ~14 GW Batch Zero-eligible; BTM studies | 19.7% (H1 2025) | 15 MW by year-end 2026 (H1 2025) | Land not sourced; C&W top-tier #3 |
| West Texas | Gas plus wind; planned 765 kV, $9.4B, 1,100-mile backbone | n/a | 2.9 GW | Land not sourced; Stargate Abilene >5 GW plan; Poolside/CoreWeave 2 GW |
| Corpus Christi, South and East Texas | Not sourced this pass | — | — | East Texas: Angelina County Res. 010-26; non-ERCOT status under the pauses "undefined" (DLA Piper) |
GR1D's weighted site scorecard
This is our method, not an industry standard: eleven criteria, 100 points, each with a data source and a pass/fail gate. A site advances at 75 points or more with every gate passed; one gate failure is a hold regardless of score.
| Criterion | Weight | Data source | Pass/fail gate |
|---|---|---|---|
| Power: distance and voltage | 15 | TDSP GIS, HIFLD, site visit | ≤3 miles to ≥138 kV; fail at >5 miles |
| Power: queue and classification | 12 | ERCOT and TDSP filings, PUCT dockets | Classified at rung 2 or higher |
| Power: behind-the-meter option | 8 | Pipeline maps, TCEQ permit-by-rule eligibility | Gas interconnect feasible in ≤18 months |
| Land and physical | 15 | FEMA NFHL, USACE, Phase I ESA, geotech | Outside 100-year floodplain; no RECs |
| Entitlement and permits | 10 | City code, ETJ map, TCEQ status | By-right or county land; no SUP or ban |
| Fiber | 10 | Carrier LOAs, dark-fiber quotes | ≥2 diverse paths, ≥3 carriers |
| Water | 8 | GCD and utility will-serve, TWDB regional plan | Closed-loop feasible; will-serve letter |
| Community and politics | 10 | Commissioners court minutes, Data Center Watch | No active resolution or moratorium |
| Market depth | 7 | CBRE, JLL, Cushman & Wakefield | Metro vacancy <5% or named anchor |
| Hazards | 3 | NOAA severe-storm and hurricane maps, FEMA | Design basis documented |
| Labor | 2 | BLS, ABC metro data | Electrician pool within 60 miles |
The low-weight rows still carry numbers: MS Amlin finds 56% of 670 planned US data centers, about $800 billion, in high-risk states, 51% of them in severe convective storm zones and 21% in hurricane zones (TechRadar, Jun 2026); TransRe rates Texas exposure "elevated" since Winter Storm Uri (TransRe, Jun 2026); 57% of data center projects were delayed in 2025 (JLL via Data Center Frontier). The weights are judgment, not regression, and a 75-point site still waits if its transformer slot slips; the scorecard orders the diligence spend, it does not replace it.
Red flags and credibility builders
Red flags (kill or discount): power "nearby" with no utility study, or a queue position with no classification; more than 5 miles to 138 kV; a single fiber path; open-loop cooling in a drought-declared county; a FEMA special flood hazard area; a city ban or special-use-permit regime, or a county with an active resolution; §151.359 value in the pro forma past 2027; a TCEQ permit on the critical path during the pause; co-location behind an existing generator, which after Docket 59220 means uncompensated curtailment and a PUCT review at 36 to 60 months.
Credibility builders: a utility load study and classification letter (rung 2); a transformer slot and posted security (rung 3); an executed interconnection or supply agreement with a date, or BTM gas with a pipeline interconnect and an issued air permit (rung 4); carrier letters of availability on two routes; a will-serve letter and a closed-loop design; a clean Phase I ESA, a geotechnical report and a FEMA determination outside the 100-year floodplain; a county road-use agreement; entitled, pre-permitted status, which is what the 15–20% premium pays for.
Frequently asked questions
What are the most important data center site selection criteria in 2026?
Speed to power first, then land, fiber, permits, community risk, water, market depth, hazards and labor. JLL calls speed to power the primary criterion for 2027 deliveries; Cushman & Wakefield measures new large-load power delivery at about 4.4 years against buyer expectations of 18 to 24 months.
What does ERCOT's 75 MW threshold mean for my site?
At 75 MW or more at one site you are an SB 6 large load: Batch Zero study, a $100,000 fee, $50,000 per MW of security, backup-generation disclosure, curtailment obligations and, since August 3, 2026, a paused Batch Zero study, final classification and energization approval. Below 75 MW you stay in your utility's process.
Where are the best places to build a data center in Texas?
Dallas–Fort Worth is Cushman & Wakefield's number-one market worldwide, with sub-1% vacancy and 3,202 MW under construction, but Oncor's queue is the deepest. Austin–San Antonio is the top secondary market at 2.3% vacancy; Houston has 19.7% vacancy; West Texas leads tertiary markets with 2.9 GW under construction.
Can a Texas county stop a data center?
Not by zoning. Counties have no zoning power and work through platting, roads, drainage and tax abatements. Cities can, under chapter 211, and San Marcos banned data centers in June 2026. Counties are asking the Legislature for setback, noise and water authority in the session that opens January 12, 2027.
Is TCEQ issuing data center permits right now?
Not officially. Since September 21, 2026, TCEQ has paused permits sought by data center projects until ERCOT's review ends, expected mid-December, and on October 19 it said it had issued none. FracTracker Alliance's records show stormwater coverages and generator reviews still moving. Treat an application on file as a plan, not a permit.
What is powered land, and how is it priced versus raw land?
Land with entitlements and a documented path to utility power, ideally a signed interconnection agreement. In DFW, pre-entitled, power-reserved sites carry a 15–20% premium over raw land at $150,000–400,000 per acre; in primary US markets powered land averaged about $584,000 per MW in 2026, up 51% in a year (Cushman & Wakefield, Sep 2026).
Sources
- JLL's 2026 Global Data Center Outlook: navigating the AI supercycle, power scarcity and structural market transformation — Data Center Frontier, 2026-01-08
- Why the world's top data center market is now in Texas — Propmodo, 2026-05-20
- JLL: the perfect data centre land acquisition plan — Datacentre Magazine, 2026-01-16
- How powered land is reshaping data center development — Foley & Lardner, 2026-08-04
- Power availability now determines where data centers get built — Data Center Knowledge, 2026-09-09
- Texas hits pause on data center grid connections amid growing oversight push — Troutman Pepper Locke, 2026-08-04
- ERCOT data center interconnection pause and Docket 59220 — Global Data Center Hub, 2026-08-26
- Batch Zero Update (Board item 14) — ERCOT, 2026-09-11
- PUCT sets financial commitments for data center interconnection; Governor pauses permits — White & Case, 2026-09-25
- What Governor Abbott's data center audit directive means for ERCOT and the Batch Zero study process — Gibson Dunn, 2026-08-14
- ERCOT sets new peak demand record — EIA, 2026-08-03
- Governor Abbott expands data center permitting pause — DLA Piper, 2026-09-25
- Governor Abbott orders TCEQ to pause all permit issuance for data center projects — Bracewell, 2026-09-23
- How to choose a data centre location — datacentres.com, 2026
- Data center site selection — Build.inc, 2026-03-29
- Dallas–Fort Worth data centre market: 1,340 MW live as ERCOT queue and Oncor substations slot — datacentres.com, 2026-08-30
- North America Data Center Trends H1 2025: Austin–San Antonio — CBRE, 2025-09-08
- North America Data Center Trends H1 2025: Houston — CBRE, 2025-09-08
- CenterPoint expects 14 GW of Texas large-load requests to qualify for Batch Zero — Utility Dive, 2026-07-28
- Logix ramps up fiber networks as Texas data centers boom — Data Center Knowledge, 2026-02-23
- Texas data center boom could consume up to 161 billion gallons of water annually by 2030 — HARC, 2026-01-21
- Texas water plan ignores data center surge — E&E News, 2026-05-20
- Abbott recommends sweeping data center regulation, including eliminating sales tax exemption — Click2Houston, 2026-06-10
- San Marcos becomes first Texas city to ban data centers, testing its local control — KBTX / Texas Tribune, 2026-06-30
- West Texas a key focus for AI — The Center Square via AOL, 2025-10-20
- How are data centers in Houston hurricane-proofed? — TRG Datacenters, 2026-04-14
- Gov. Abbott orders data centers to pay own power grid costs; rural counties face limited authority — KBTX, 2026-06-10
- Angelina County commissioners vote to ask state for authority to regulate data centers — KLTV, 2026-07-14
- Resolution R-04-2026 on data centers — Anderson County Commissioners Court, 2026
- Community opposition emerges as new gatekeeper for AI data center expansion — Data Center Frontier, 2026-03-09
- Site selection considerations for hyperscale data centers — Reed Smith, 2025-06-24
- Data centers: sales and use tax exemption — Texas Comptroller of Public Accounts, 2026-10-14
- Senate Finance Committee testimony on data center tax breaks — Public Citizen, 2026-07-27
- Bill analysis, H.B. 3104 (88th Legislature), engrossed — Texas Senate Research Center, 2023-05-12
- Texas counties push for say in where data centers can be built — KXII, 2026-08-11
- Data Center Watch Q1 2026 report — Data Center Watch, 2026
- Dallas–Fort Worth dethrones Virginia as the world's top data center market — Dallas Innovates, 2026-08-18
- North America data centers feel the squeeze as vacancy shrinks to 1 percent: JLL — W.Media, 2026-02-23
- North American data center demand continues to outpace supply despite record construction activity — CBRE, 2026-08-27
- 56% of new US data centers could be built in high-risk disaster-prone states — TechRadar, 2026-06-08
- Build it and they (storms) will come — TransRe, 2026-06
- 2026 Data Center Development Cost Guide — Cushman & Wakefield, 2026-09-03
- Texas said it would halt data center permits; the state is pushing ahead anyway — 404 Media, 2026-10-19
- Texas continued data center permitting after the governor's pause — FracTracker Alliance, 2026-10-19
Building or financing an AI data center in Texas?
GR1D develops powered-shell and turnkey AI data centers — 20 MW to 150 MW sites with power, fiber and entitlements solved before the first rack arrives. See how we build, browse our sites or talk to us.